
Daily brief · 2026-11-10
Historical edition · New York time. These observations reflect their published date, not current market conditions.
Hot CPI meets the reclaim: core +0.3% puts Waller's bigger-hike test live
narrow pass under event pressure: SPY closed above $750.36, then a hot CPI print pulled premarket back under it (unfinished)
Chart analysis
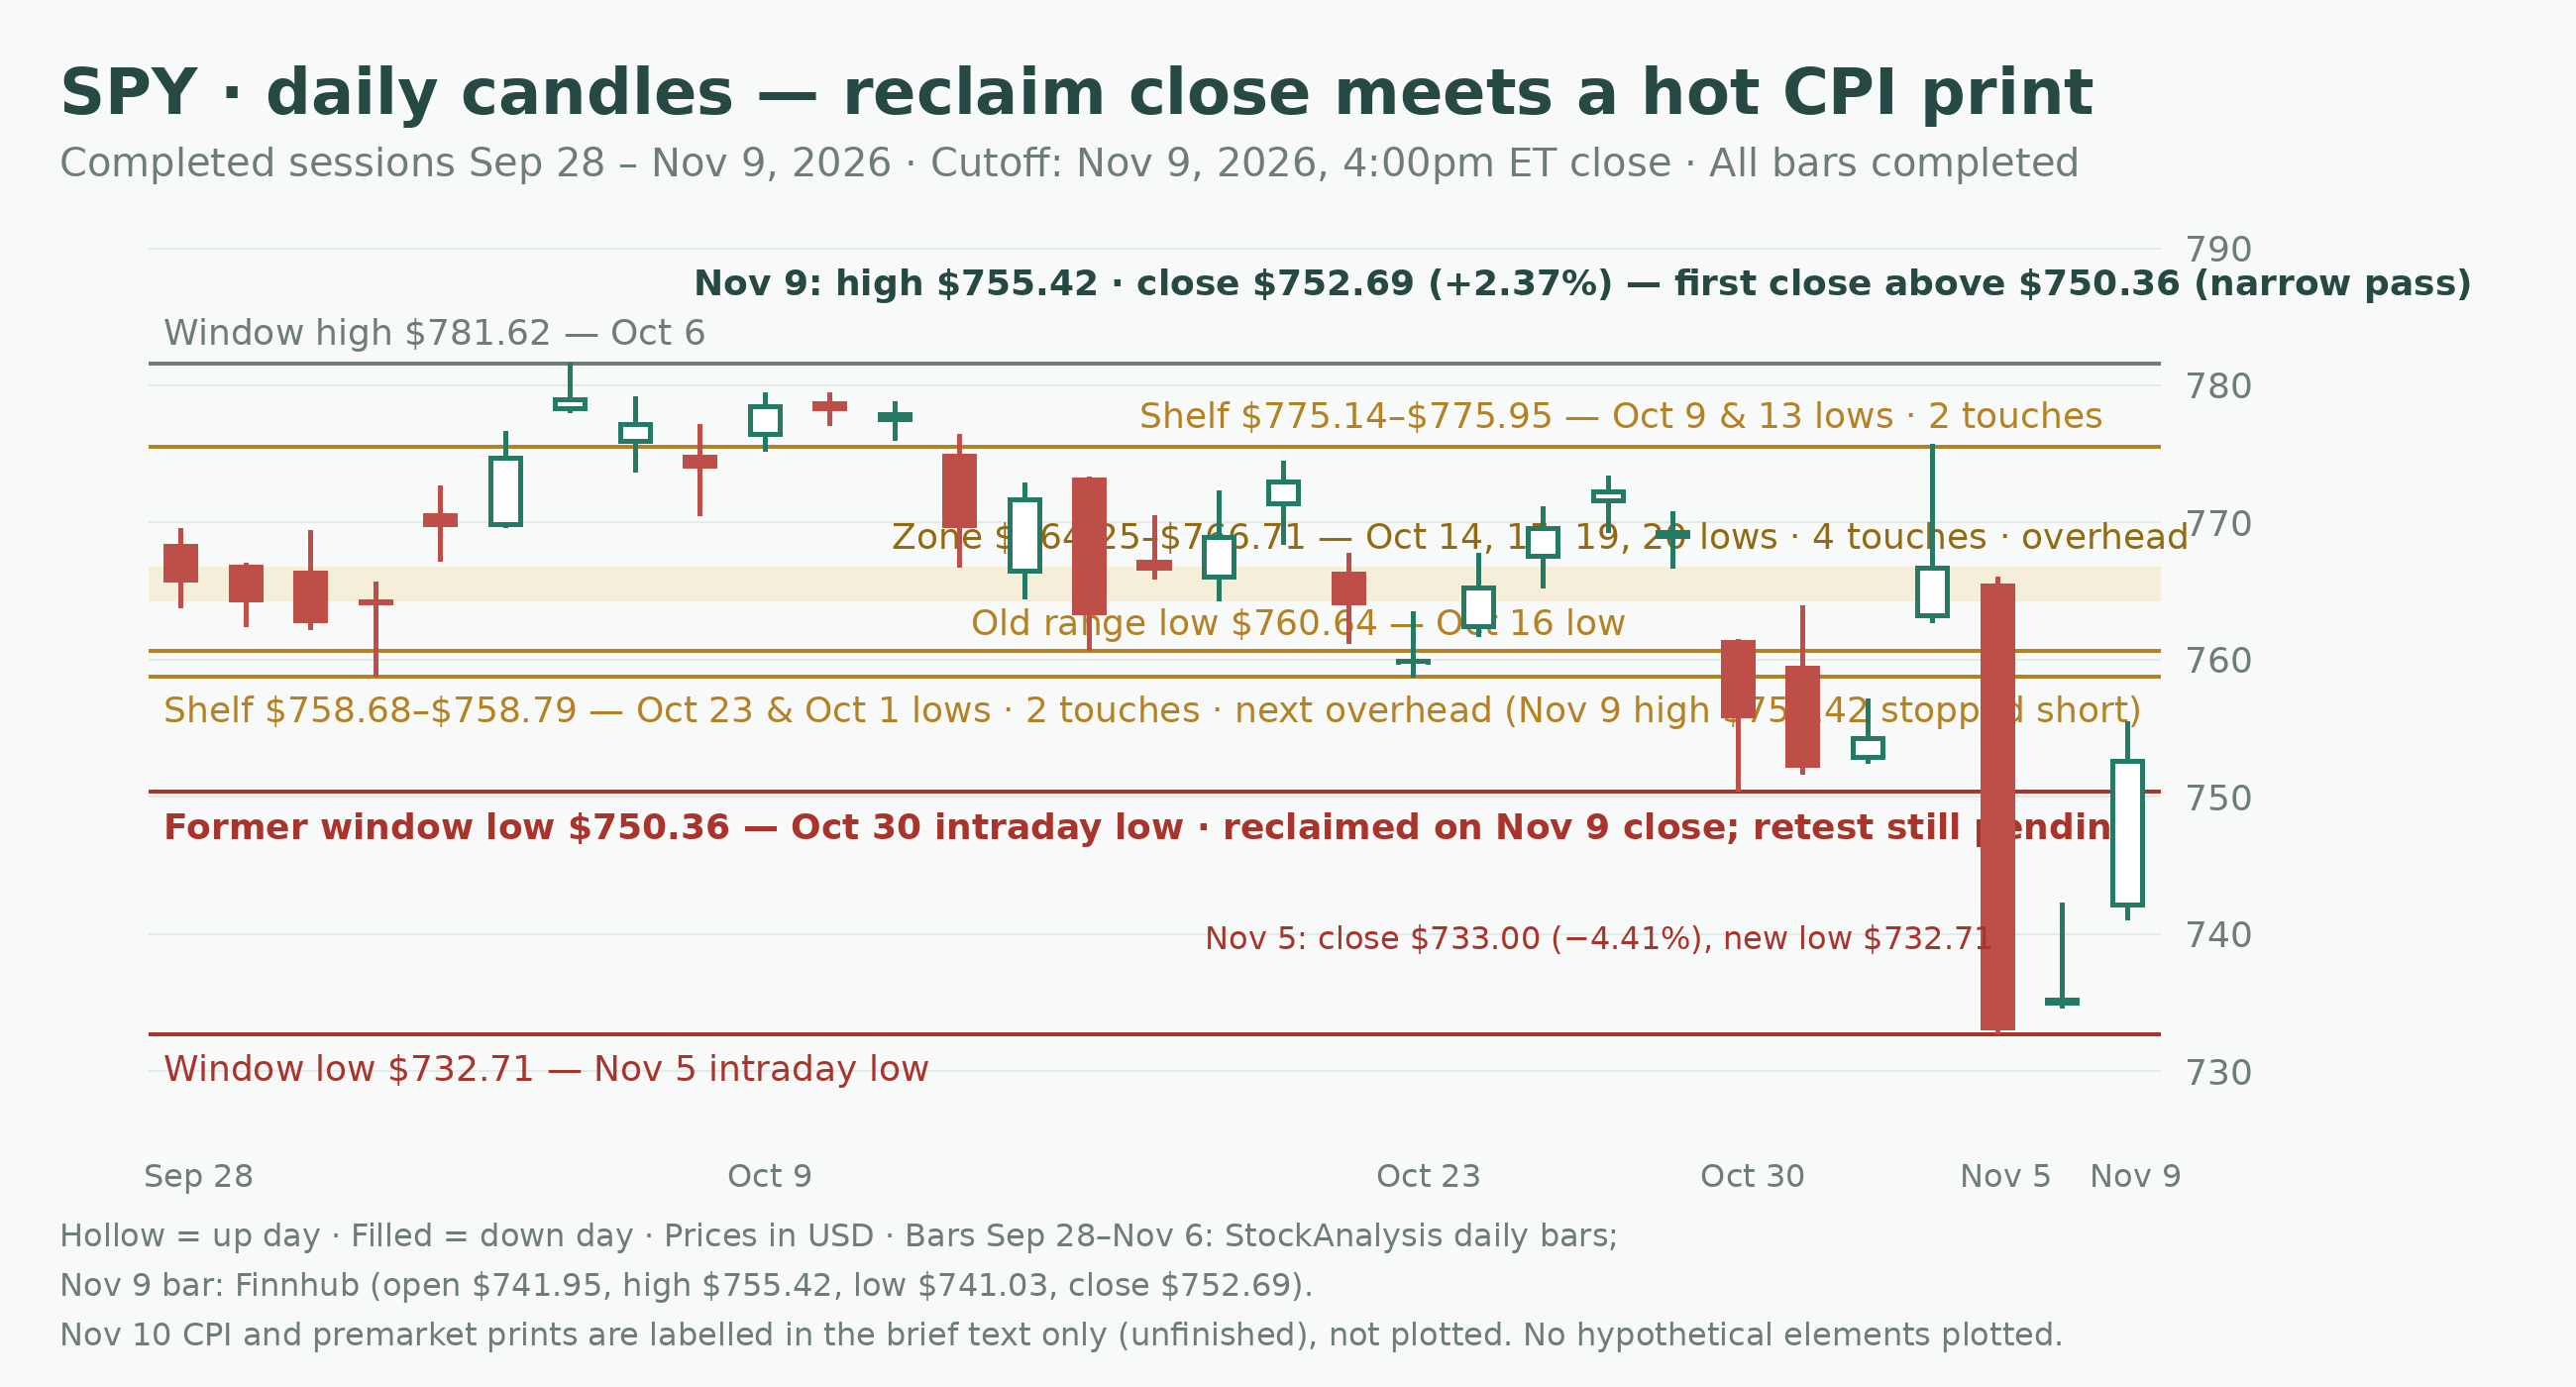
Published chart · Tap chart to enlarge.
Published chart lesson
A reclaim is graded by the closes that follow it, not by the first trade after the next headline. SPY's former window low is $750.36, the Oct 30 intraday low (StockAnalysis daily bars); Monday's completed bar (Finnhub) closed at $752.69, above the line, which is a narrow pass — and this morning's premarket print of $749.04 at 8:39am ET (Finnhub, unfinished), after the 8:30am ET CPI release, trades below the line again without cancelling that close, because a retest is graded on completed closes, not on unfinished premarket trades. The retest question is therefore still open, and today's completed close is its first answer. What would weaken or change the lesson: a completed close today that holds above $750.36 after testing it from above would upgrade the reclaim toward repair; a completed close back below $750.36 would grade Monday's close as a false reclaim and leave the lesson intact.
Brief analysis source: SPY daily, StockAnalysis and Finnhub, Nov 9 2026 . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- October CPI printed hot at 8:30am ET: headline +0.4% on the month against +0.3% expected, core +0.3% against +0.2% expected, with no 12-month figure published because October 2025 prices were never collected (BLS) — and core landed exactly on the 0.3% line Governor Waller had set for considering a 50 basis point December hike.
- On completed bars, Monday was a narrow pass: SPY closed at $752.69, up 2.37% (Finnhub), $2.33 above the former window low at $750.36, with breadth flipped to 420 advancing against 78 declining (ChartRow) — but no retest has held yet, and SPY's $749.04 premarket print at 8:39am ET (Finnhub, unfinished) trades back below the line after the print.
- Options learning point: the event risk was dated and it arrived — any premium sold before an 8:30am ET inflation print must survive the print itself, and a hot core reading at a Fed governor's stated trigger changes the pricing question from whether December brings a hike to how large it is, while waiting puts no option premium at risk.
Read the full brief and sources
- The 8:30am ET release leads, and it came in hot. October consumer prices rose 0.4% on the month, above the +0.3% expected and down from September's +0.6%, while core prices — excluding food and energy — rose 0.3%, above the +0.2% expected and matching September's +0.3% (Bureau of Labor Statistics release, reported at 8:35am ET). There is no 12-month figure to soften or sharpen the read: BLS never collected October 2025 prices during the shutdown, so no annual change was published for the headline or core index. Inside the report, shelter rose 0.3% and accounted for over 30% of the monthly gain, energy rose 0.7% with gasoline up 1.0%, food rose 0.5%, and used cars and trucks fell 1.2%. The print landed exactly on the line Fed Governor Christopher Waller had drawn in London hours earlier: he said he was leaning toward a 25 basis point hike in December even if inflation improved, and that a 50 basis point move should be considered if core inflation came in around 0.3% or higher — core printed 0.3%. The first market snapshot after the release showed the strain: SPY (the S&P 500 ETF) traded at $749.04 in premarket at 8:39am ET, down 0.48% from Monday's close (Finnhub, unfinished) — back below the $750.36 line on an unfinished basis, nine minutes after the data. Before the print, futures had been split and calm at 7:13am ET: S&P 500 futures at 7,575.25, up 0.01%, Dow futures up 0.37% and Nasdaq-100 futures down 0.39% (CNBC quotes, via desk notes).
- Start with the widest frame, on completed daily bars. The completed Sep 28–Nov 9 window for SPY (the S&P 500 ETF) runs from $781.62 (the Oct 6 high) down to $732.71 (the Nov 5 intraday low). Monday's completed bar opened at $741.95, reached $755.42, fell to $741.03 and closed at $752.69, up 2.37% (Finnhub, completed bar), on 50.3 million shares. Behind the ETF, the S&P 500 index rose 2.35% to 7,549.94, the Nasdaq Composite rose 2.74% to 25,253.14 and the Dow Jones Industrial Average rose 1,104 points, or 2.15%, to 52,389.75 (Monday closing prints) — the S&P 500's best day since April. QQQ (the Nasdaq-100 ETF) closed at $679.35, up 3.54% (Finnhub regular-session close). Participation flipped hard versus Friday: 420 S&P 500 members advanced and 78 declined at Monday's close, and 69% of members sat above their own 50-day average (ChartRow, Nov 9 close) — against 183 advancing, 316 declining and 63% above the average on Friday — so Monday's rise, unlike Friday's bounce, was carried by most of the index, with 27 new 52-week highs against 2 new lows (ChartRow).
- Grade Monday's close against the frame, in the order the tests come. The close at $752.69 sits $2.33 above $750.36, the Oct 30 intraday low that served as the window low until last Thursday — so the broken floor was reclaimed on a completed close for the first time. That is a narrow pass only: confirmation is graded, and the higher grade — a retest of $750.36 from above that holds on a completed close — has not happened yet. The push also stopped short of the next line: Monday's high of $755.42 (completed bar) never reached the thin shelf at $758.68–$758.79 (the Oct 23 and Oct 1 lows, two touches), with the old range low at $760.64 (the Oct 16 low), the zone at $764.25–$766.71 (the Oct 14, Oct 15, Oct 19 and Oct 20 lows, four touches) and the shelf at $775.14–$775.95 (the Oct 9 and Oct 13 lows, two touches) stacked above it. Today's session is the retest candidate, and the hot CPI has set its terms: this morning's premarket print at $749.04 (Finnhub, unfinished) trades below the line again, but an unfinished premarket trade neither holds a retest nor cancels a completed close — today's completed close is the grade. Around the edges, the VIX sat at 19.99 at 7:23am ET (CNBC), WTI crude was $85.12 a barrel, down 1.99%, at 7:14am ET (CNBC), spot gold traded at $4,115.12 an ounce early Tuesday and bitcoin traded near $74,080, down about 1.3% — context, not a grade: none of it moves a single completed US bar.
- Rates were already leaning hawkish before the print, and the print gave them no reason to soften. At 7:24am ET, before the release, the 10-year Treasury yield was 4.892%, up 0.03 on the morning, and the 2-year yield was 4.618%, up 0.071 (CNBC) — the day's biggest pre-print moves were at the short end, coinciding with Waller's London remarks. December hike pricing had firmed in step: Reuters put the CME FedWatch implied odds of a 25 basis point hike at 82.2% on Tuesday morning, up from 74% a week earlier, with market pricing late Monday reported near 85% — snapshots differ by source and time, the level and direction do not. After the 8:30am ET release, yields moved off their lows with the biggest moves again at the short end, the dollar rose and stocks fell, as hike odds were reported moving toward near-certainty for a 25 basis point move (post-release coverage) — those are simultaneous moves, recorded as they coincided, not proof of a single cause. The bond market gets a second test today: the Treasury auctions 10-year notes at 1:00pm ET. Retail sentiment still cannot grade any of this: the latest AAII survey (bullish 34.1%, bearish 48.4%, week ended Nov 4) closed before last Thursday's break, Friday's bounce and Monday's rally; the new survey publishes Thursday morning.
- This morning's BMO earnings, verified from official releases: TransDigm (TDG) reported GAAP EPS of $10.33, or $12.44 adjusted, on net sales of $2.99 billion, up 23% (SEC filing release). Sea Limited (SE) reported GAAP diluted EPS of $0.78 per share on revenue of $8.58 billion, up 43.4%, with net income of $502.5 million (Business Wire release). On Holding (ONON) reported IFRS diluted EPS of CHF 0.48 per Class A share, or CHF 0.54 adjusted, on net sales of CHF 931.4 million, up 17.2% — figures in Swiss francs, as reported (company release). Venture Global (VG) reported diluted EPS of $0.96 on revenue of $4.8 billion and raised its full-year adjusted EBITDA guidance to $10.0–$10.3 billion (company release). The rest of today's 42-name BMO slate stays in the site's earnings checks as pending, not silently dropped. Tonight's after-hours reports — including CoreWeave — come after today's 4:00pm ET close, so they cannot grade today's session; they are separate, later evidence.
Analyst interpretation: Monday earned a narrow pass and Tuesday's print immediately set the retest. The reclaim close at $752.69 was real — broad, on most of the index, and the first completed close above $750.36 since the break — but it was $2.33 of clearance with no retest behind it, and the recovery stopped $3.26 short of even the next shelf at $758.68. Through a conservative put-seller's lens, the constraint is the same calendar, now one step further along: core inflation printed 0.3%, the exact reading a Fed governor had named hours earlier as the trigger for considering a larger December move, and December pricing that was already 82–85% for a quarter-point hike leaves the open question at the size of the move, not its existence. A hypothetical teaching example only — not a market quote and not a trade: in the Options Industry Council's terms, a put credit spread sells one put and buys a lower-strike put with the same expiry; sold for a hypothetical $1.25 credit on a $5-wide spread, its maximum gain is $1.25, its maximum loss is $3.75 plus fees, and its breakeven is the short strike minus $1.25. If the underlying expires between the strikes with the spread worth $2.00, the loss is $0.75 before fees — the full $3.75 is lost only at or below the long strike — and the short put carries assignment risk before expiry. A larger credit is not a higher win rate; the breakeven condition is what has to hold, and a spread sold into a dated print has to hold it through the print and through the repricing that follows it. Waiting puts no option premium at risk; its cost is possibly missing further recovery, not a spread loss. A research question to study, not a recommendation: after a first reclaim close above a broken floor, compare how often the next session's completed close held above the line when a hot inflation print landed in between, against how often the reclaim failed first when the print came in soft. With the print now known and today's completed close still ahead, waiting is a valid position.
A completed close today holding above $750.36 — the Oct 30 intraday low reclaimed on Monday's close — after testing that line from above would be the first held-retest evidence and would upgrade the narrow pass; a later completed close above $758.79, the top of the $758.68–$758.79 shelf built from the Oct 23 and Oct 1 lows, would extend the repair toward the old range low at $760.64 and the zone at $764.25–$766.71.
A completed close back below $750.36 would grade Monday's reclaim a false reclaim and return the frame to trading under the broken floor; a completed close below $741.03, Monday's intraday low on its completed bar, would show the reclaim session itself being unwound, with Friday's $735.29 close (Finnhub series) and the $732.71 window low (the Nov 5 intraday low) as the next completed-bar references below.
Sources
- October CPI (BLS, released Nov 10, 8:30am ET): headline +0.4% on the month (vs +0.3% expected, +0.6% in September), core +0.3% (vs +0.2% expected); shelter +0.3% accounting for over 30% of the gain, energy +0.7%, gasoline +1.0%, food +0.5%, used cars and trucks -1.2%; no 12-month change published — ZeroHedge (BLS release summary)Nov 10, 2026, 8:35am ET
- Inflation slowed on the month but beat forecasts: consumer prices rose 0.4% in October, down from 0.6% in September, above the Cleveland Fed nowcast of +0.24%; no annual rate reported because last October's data was never collected — USA TodayNov 10, 2026 (developing report, checked about 8:45am ET)
- Desk notes Nov 10: at 7:13am ET S&P 500 futures 7,575.25, up 0.01%, Dow futures up 0.37%, Nasdaq-100 futures down 0.39% (CNBC); at 7:24am ET the 2-year yield was 4.618% and the 10-year 4.892% (CNBC); WTI crude $85.12, down 1.99%, at 7:14am ET; VIX 19.99 at 7:23am ET — Simon Hertz desk notes (CNBC quotes)Nov 10, 2026, 7:13–7:24am ET
- SPY Nov 9 completed daily bar: open $741.95, high $755.42, low $741.03, close $752.69, +2.37% (previous close $735.29); SPY premarket price $749.04, down 0.48%, at 8:39am ET Nov 10 (unfinished) — FinnhubNov 9, 2026, 4:00pm ET close; Nov 10, 2026, 8:39am ET premarket
- QQQ regular-session close $679.35, up 3.54% on Nov 9 — FinnhubNov 9, 2026 regular-session close
- SPY daily bars (open/high/low/close) Sep 28–Nov 6, 2026: window high $781.62 (Oct 6), former window low $750.36 (Oct 30 intraday low), window low $732.71 (Nov 5 intraday low) — StockAnalysisNov 6, 2026, 4:00pm ET close (completed bars through Nov 6)
- Monday closing prints: Dow Jones Industrial Average up 1,104 points, or 2.15%, to 52,389.75; S&P 500 up 2.35% to 7,549.94; Nasdaq Composite up 2.74% to 25,253.14 — BeInsure market coverage (Monday closes)Nov 9, 2026, 4:00pm ET close
- S&P 500 breadth at the Nov 9 close: 420 advancing, 78 declining; 69% of S&P 500 members above their own 50-day average (346 of 499 eligible); 27 new 52-week highs, 2 new lows — ChartRowNov 9, 2026, 4:00pm ET close
- CME FedWatch implied odds of a December 25bp hike at 82.2%, up from 74% a week earlier (Reuters); Governor Waller favored a December hike even if inflation cooled and a possible 50bp move if it came in hot; the 2-year yield rose 3.3 basis points to 4.58% in earlier snapshots — StockVolt (Reuters reporting)Nov 10, 2026 (pre-release morning)
- Futures steady before CPI as Waller floats a half-point hike: markets priced about an 85% chance of a December hike late Monday (Reuters); the 10-year Treasury yield rose 2 basis points to 4.882% early Tuesday (CNBC); Waller would back at least a quarter-point increase and consider a half-point move if core prices rise 0.3% or more — World Money Roadmap (Reuters, CNBC)Nov 10, 2026, morning ET (pre-release)
- Spot gold traded at $4,115.12 an ounce early Tuesday; traders priced an approximately 84% probability of a December Fed hike ahead of the release (CME FedWatch figures cited) — MarketInsiderNov 10, 2026, 02:38 GMT
- Bitcoin traded near $74,080, down about 1.3%, as Waller backed a December 25bp hike — Aieon (CoinDesk, Cointelegraph reporting)Nov 10, 2026
- AAII Sentiment Survey, week ended Nov 4, 2026: bullish 34.1%, neutral 17.5%, bearish 48.4% — AAII (survey closed before the Nov 5 session)Nov 5, 2026 (survey week ended Nov 4, 2026)
- TransDigm fiscal Q4 2026: net sales $2.99 billion, up 23% year over year; net income $586 million; EPS $10.33 and adjusted diluted EPS $12.44, up 15% — TradingView News (company SEC Form 8-K release)Nov 10, 2026
- Sea Limited Q3 2026: GAAP revenue US$8.6 billion, up 43.4%; net income US$502.5 million, up 34.0%; EPS attributable to ordinary shareholders: basic US$0.81, diluted US$0.78; adjusted EBITDA US$931.3 million — Business Wire (official release)Nov 10, 2026
- On Holding Q3 2026: net sales CHF 931.4 million, up 17.2%; net income CHF 162.8 million, up 36.9%; diluted EPS Class A CHF 0.48, adjusted diluted EPS Class A CHF 0.54; gross margin 72.6% including CHF 52.6 million of U.S. tariff refunds — On Holding (official release)Nov 10, 2026
- Venture Global Q3 2026: revenue $4.8 billion, up 43%; net income $2.5 billion; Consolidated Adjusted EBITDA $2.6 billion; full-year 2026 guidance raised to $10.0–$10.3 billion — Venture Global (official release)Nov 10, 2026
- Week ahead Nov 9-13: Wednesday is Veterans Day with the Treasury market closed; Friday brings October PPI — Independent Investor week aheadWeek of Nov 9-13, 2026