
Daily brief · 2026-11-04
Historical edition · New York time. These observations reflect their published date, not current market conditions.
Futures jump after the sweep — the lost zone still grades the open
break in force, day four: premarket over the shelf but under the zone — ADP firm, ISM services and Qualcomm/Arm ahead
Chart analysis
Published chart · Tap chart to enlarge.
Published chart lesson
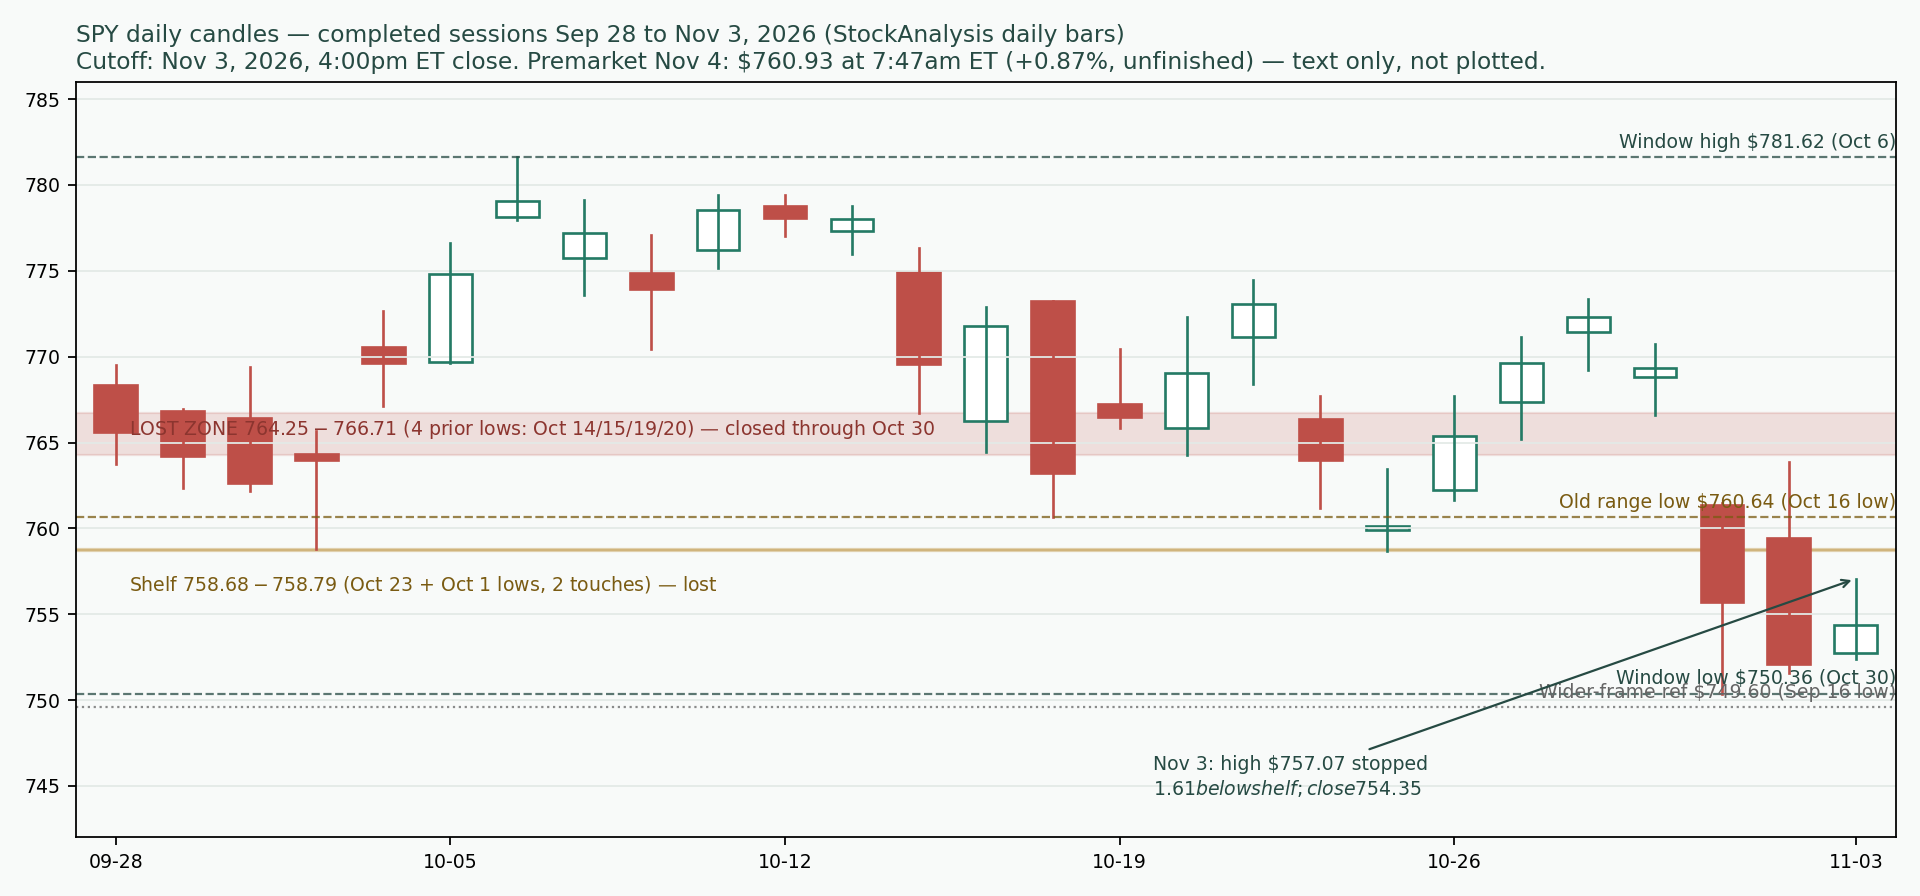
A premarket move above a lost shelf schedules a test; it does not pass one. Repair is graded in two steps on completed bars: first a completed close back above the level that was lost, then a retest of that level from above that holds. SPY's shelf at $758.68–$758.79 is built from the Oct 23 and Oct 1 completed lows (StockAnalysis daily bars), and its old range low is $760.64 (the Oct 16 low). Tuesday's completed bar stopped at $757.07, below the shelf, and closed at $754.35. This morning's premarket print of $760.93 (7:47am ET, unfinished) trades above both the shelf and $760.64 — an observation about an unfinished bar, not established support and not a reclaim. What would weaken the lesson: a completed close today above $760.64 that is then held on a retest would be the first graded repair evidence, and a completed close above $766.71, the zone top, would go further; a completed close back below $758.68 would instead show the morning's move was another intraday probe that failed.
Brief analysis source: SPY daily bars, StockAnalysis, Nov 3, 2026 (completed close); premarket print Nov 4, 2026, 7:47am ET (unfinished) . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- Tuesday's completed bars changed nothing on the map: SPY closed at $754.35, up 0.30% (StockAnalysis), a third straight close below the lost $764.25–$766.71 zone — but this morning's premarket print of $760.93 (7:47am ET, unfinished) sits above the $758.68–$758.79 shelf and the $760.64 old range low, so today's completed close is the first real repair test.
- ADP led the morning: October private payrolls rose 86,000 against 69,000 expected, with September revised to 86,000 (Reuters, 8:15am ET); the ISM services index follows at 10:00am ET, the 10-year yield eased to about 4.91–4.92%, and December hike pricing firmed to 76.9% (CME FedWatch, Nov 4) ahead of Friday's jobs report.
- Options learning point: a premarket gap over a lost shelf is an unfinished bar, not a reclaim — repair is graded on a completed close and a held retest, and with ISM services today, Qualcomm and Arm after the close, jobless claims Thursday and payrolls Friday, any premium sold must survive four more dated event prints, while waiting puts no option premium at risk.
Read the full brief and sources
- Start with the widest frame, on completed daily bars. SPY (the S&P 500 ETF) on Tuesday opened at $752.73, reached $757.07, fell to $752.39 and closed at $754.35, up 0.30% (StockAnalysis daily bars, completed bar) — a third straight close below every shelf the autumn window built, on 32.9 million shares, lighter than Monday's 50.8 million. The completed Sep 28–Nov 3 window runs from $781.62 (the Oct 6 high) down to $750.36 (the Oct 30 intraday low), and its weekly closes have stepped down four weeks in a row: $778.57, $763.25, $759.97, $755.72, with this week's two completed bars at $754.35. The S&P 500 index itself closed at 7,568.96, up 0.37% (eOption closing recap, Nov 3). QQQ (the Nasdaq-100 ETF) opened at $684.39, reached $688.69, fell to $683.18 and closed at $685.28, up 0.62% (completed bar) — a steadier day than SPY's, but still far below its own autumn levels. Nothing in Tuesday's completed bars repaired the Oct 30 closing break; the low held, and that is all they showed.
- Inside that frame, this morning hands the chart a new test — at a higher shelf than yesterday's. The lost zone is $764.25–$766.71, built from four prior completed lows (Oct 14 at $766.71, Oct 15 at $764.43, Oct 19 at $765.82, Oct 20 at $764.25). Below it sit the thin shelf at $758.68–$758.79 (the Oct 23 and Oct 1 lows, two touches) and the old range low of $760.64 (the Oct 16 low). Tuesday's high of $757.07 stopped $1.61 below the shelf's bottom. This morning SPY traded at $760.93 in premarket at 7:47am ET, up 0.87% (StockAnalysis, unfinished) — above the shelf top by $2.14 and above $760.64 by $0.29, but still $3.32 below the zone's bottom. QQQ traded at $692.02 at 6:55am ET, up 0.98% (unfinished). Index futures pointed the same way: Dow futures up about 1.8%, S&P 500 futures up about 0.9% and Nasdaq-100 futures up about 0.2% (Investopedia, this morning) — a reversal from the overnight lows, when Nasdaq-100 futures had fallen as much as 2.4% and S&P 500 futures 1.4% (Reuters, 4:22am ET snapshot). A premarket print grades nothing: repair is graded on a completed close above the shelf, then the zone, not on where the unfinished morning bar trades.
- This morning's data lead is the ADP employment report, released at 8:15am ET: private employers added 86,000 jobs in October, above the 69,000 economists polled by Reuters expected, while September was revised down to 86,000 from 90,000 (Reuters). The site's economic calendar lists no 8:30am ET release today. The next scheduled test is the ISM services index at 10:00am ET, with consensus at 54.7–54.8 against 54.9 in September (CME Econoday), alongside the Treasury's quarterly refunding announcement. The 10-year Treasury yield eased as the election result landed: it fell 3.5 basis points to 4.914% in the 7:46am ET update (Dow Jones Newswires via Morningstar), with Investopedia putting it at 4.92%, down from about 4.97% on Tuesday night — lower, but still near 5%. December rate pricing firmed the other way: CME FedWatch on Nov 4 put a 25bp hike at the Dec 9 meeting at 76.9% (BlockBeats reading of CME FedWatch), up from 74.9% on Nov 3. Under the surface on Tuesday, participation stayed narrow: only 185 S&P 500 members rose against 311 that fell, with 67% of members above their 50-day average (334 of 498 eligible) and 63% above their 200-day average (ChartRow, Nov 3 close) — the index rose because its largest chip names rose. Retail sentiment is context only: the AAII survey for the week ended Oct 28 (bullish 37.8%, bearish 41.4%) predates the break, and the new survey publishes Thursday morning.
- Overnight, the midterm elections delivered the result the futures are trading on: Democrats won control of both the House and the Senate (Associated Press race calls). Asia whipsawed and then recovered: Japan's Nikkei finished about 1.5% lower and Taiwan's benchmark about 0.8% lower, while South Korea's Kospi erased its losses to trade 0.3% higher, the Hang Seng rose 1.3% and the Shanghai Composite gained 1.7% (Dow Jones Newswires via Morningstar, 2:04am ET); a later update had Shanghai up 2.2%, the Hang Seng up 1.45% and European indexes also higher (Dow Jones Newswires via Morningstar, 6:16am ET). In that later update Brent crude fell 1.4% to about $102.20 a barrel, gold rallied back above $4,000 an ounce and bitcoin hovered around $78,400; Investopedia this morning put Brent at $101.65, down about 1.9%, WTI at $94.67, down about 1.5%, and bitcoin near $78,000 (CoinDesk). The election changes the policy backdrop; what it changes for this chart is decided by completed closes, starting with today's.
- This morning's BMO earnings, verified from official releases: McDonald's reported diluted EPS of $3.51 and, excluding restructuring charges, $3.57, on revenues of $7,157 million (PR Newswire). Uber reported GAAP diluted EPS of $0.25 — the figure carries a $476 million pre-tax loss on equity-investment revaluations — and non-GAAP EPS of $0.88, on revenue of $14,766 million with gross bookings up 20% to $59.8 billion (SEC 8-K). CVS Health reported GAAP diluted EPS of $1.68 and adjusted EPS of $2.09 on revenues of $108.4 billion and raised its full-year guidance (CVS Health). Emerson reported fiscal fourth-quarter GAAP EPS of $1.33 and adjusted EPS of $1.86 on net sales of $5,201 million (PR Newswire). Novo Nordisk reported, in Danish kroner per share/ADR, reported EPS of DKK 3.79 and adjusted diluted EPS of DKK 5.79 on net sales of DKK 79,195 million, with DKK 8.7 billion of non-cash impairments inside the reported figure (company announcement). Datadog reported GAAP diluted EPS of $0.32 and non-GAAP diluted EPS of $0.81 on revenue of $1,197 million, up 35% (8-K release). The rest of today's large BMO slate and the names carried from Oct 28–Nov 3 stay on the reconciliation queue, unverified, rather than recorded from secondary summaries. A question to study, not a trade: CVS raised guidance and Datadog grew revenue 35%, while the index's break is so far a large-cap story — what would today's completed closes in the growth names, and in participation, need to show for results like these to count as the start of repair rather than good news arriving inside an unrepaired break?
Analyst interpretation: overnight, the test moved up a shelf — and that is genuinely different from Monday and Tuesday, when the bounce could not even reach the shelf. But a premarket print is an unfinished bar, and this break has already produced one bounce that stopped short and closed back down. The honest grade is unchanged until a completed close says otherwise: zone lost, shelf being tested from below this morning, window low intact at $750.36. Two facts argue for patience rather than chase. First, participation: on Tuesday only 185 S&P 500 members rose while the index gained (ChartRow, Nov 3 close), so the bid is still narrow. Second, the calendar: ISM services at 10:00am ET today, Qualcomm and Arm after tonight's close, jobless claims on Thursday and the October jobs report on Friday, into a Dec 9 Fed meeting the market prices at 76.9% for a hike (CME FedWatch, Nov 4) with the 10-year yield still near 4.91%. A hypothetical teaching example only — not a market quote and not a trade: in the Options Industry Council's terms, a put credit spread sells one put and buys a lower-strike put with the same expiry; sold for a hypothetical $1.10 credit on a $5-wide spread, its maximum gain is $1.10, its maximum loss is $3.90 plus fees, and its breakeven is the short strike minus $1.10. If the underlying expires between the strikes with the spread worth $2.00, the loss is $0.90 before fees — the full $3.90 is lost only at or below the long strike — and the short put carries assignment risk before expiry. A larger credit is not a higher win rate; the breakeven condition is what has to hold. Waiting puts no option premium at risk; its cost is possibly missing a further move, not a spread loss. With the first repair test scheduled for today's close and three more event prints behind it, waiting is a valid position.
A completed close back below $758.68, the bottom of the shelf built from the Oct 23 and Oct 1 lows, would confirm the break is still in force and grade this morning's premarket move as a failed probe of the shelf. A completed close below $750.36, the Oct 30 intraday low and the bottom of the Sep 28–Nov 3 window, would confirm the break is extending, and a completed close below $749.60, the Sep 16 low, would extend it to the wider frame.
A completed close above $760.64, the Oct 16 low (the old range low), would be the first step of repair — it reclaims the old range low and the shelf, not the zone — and a later retest of $758.68–$760.64 from above that holds on a completed close would be stronger evidence. A completed close above $766.71, the zone top (the Oct 14 low), would grade the Oct 30 closing break as a probe that failed; on its own it is a narrow pass until a retest from above holds.
Sources
- SPY daily bars (open/high/low/close) and Nov 4 premarket print $760.93 at 7:47am ET (unfinished) — StockAnalysisNov 3, 2026, 4:00pm ET close (completed bars through Nov 3); premarket Nov 4, 2026, 7:47am ET
- QQQ daily bars and Nov 4 premarket print $692.02 at 6:55am ET (unfinished) — StockAnalysisNov 3, 2026, 4:00pm ET close (completed bars through Nov 3); premarket Nov 4, 2026, 6:55am ET
- Futures this morning: Dow futures +1.8%, S&P 500 futures +0.9%, Nasdaq-100 futures +0.2%; 10-year Treasury yield 4.92%; Brent $101.65 (-1.9%), WTI $94.67 (-1.5%); bitcoin near $78,000 (CoinDesk) — InvestopediaNov 4, 2026, morning ET
- Futures reversal: Nasdaq-100 futures had fallen as much as 2.4% and S&P 500 futures 1.4% overnight; at 4:22am ET Dow E-minis +0.84%, S&P 500 E-minis +0.35%, Nasdaq-100 E-minis +0.16%; AMD +6.2% premarket — ReutersNov 4, 2026, 4:22am ET snapshot (Reuters)
- ADP National Employment Report: October private payrolls +86,000 vs 69,000 expected (Reuters poll); September revised to +86,000 from +90,000 — ReutersNov 4, 2026, 8:15am ET release
- 10-year Treasury yield fell 3.5 basis points to 4.914%; two-year yield 4.603% (Tradeweb) — Dow Jones Newswires via Morningstar (2nd update)Nov 4, 2026, 7:46am ET
- Asia and Europe: Shanghai Composite +2.2%, Hang Seng +1.45%, European indexes higher; Brent about $102.20 (-1.4%); gold back above $4,000; bitcoin about $78,400 — Dow Jones Newswires via Morningstar (2nd update)Nov 4, 2026, 6:16am ET
- Asia whiplash: Nikkei about -1.5%, Taiwan about -0.8%, Kospi +0.3% after erasing losses, Hang Seng +1.3%, Shanghai Composite +1.7% — Dow Jones Newswires via Morningstar (2nd update)Nov 4, 2026, 2:04am ET
- Democrats won control of both the House and the Senate (Associated Press race calls) — Cointelegraph recap of AP resultsNov 4, 2026 (election Nov 3, 2026)
- ISM Services Index at 10:00am ET today: consensus 54.7 (range 54.0–56.3) vs 54.9 in September — CME EconodayNov 4, 2026 (pre-release consensus)
- CME FedWatch on Nov 4, 2026: 76.9% probability of a 25bp hike at the Dec 9, 2026 FOMC meeting, up from 70% — BlockBeats (CME FedWatch)Nov 4, 2026
- S&P 500 breadth at the Nov 3 close: 185 advancers / 311 decliners; 67% of members above their 50-day average (334 of 498 eligible), 63% above their 200-day average — ChartRowNov 3, 2026 close
- AAII Sentiment Survey, week ended Oct 28, 2026: bullish 37.8%, bearish 41.4% — AAIIOct 29, 2026 (survey week ended Oct 28, 2026)
- McDonald's Q3 2026: diluted EPS $3.51, $3.57 excluding charges, revenues $7,157M — PR Newswire (official release)Nov 4, 2026
- Uber Q3 2026: GAAP diluted EPS $0.25, non-GAAP EPS $0.88, revenue $14,766M, gross bookings $59.8B — SEC Form 8-K (official filing)Nov 4, 2026, 6:55am ET (8-K filed)
- CVS Health Q3 2026: GAAP diluted EPS $1.68, adjusted EPS $2.09, total revenues $108.4B; full-year guidance raised — CVS Health (official release)Nov 4, 2026
- Emerson fiscal Q4 2026: GAAP EPS $1.33, adjusted EPS $1.86, net sales $5,201M — PR Newswire (official release)Nov 4, 2026
- Novo Nordisk Q3 2026: reported EPS/ADR DKK 3.79, adjusted diluted EPS/ADR DKK 5.79, net sales DKK 79,195M — company announcement No. 65/2026 (official, Form 6-K text)Nov 4, 2026
- Datadog Q3 2026: GAAP diluted EPS $0.32, non-GAAP diluted EPS $0.81, revenue $1,197M — SEC Form 8-K release (official filing)Nov 4, 2026
Dow soars 3% after the sweep — SPY closes inside the lost zone, not above it
repair step one: shelf and old range low reclaimed on a completed close, but the zone was only pierced — Friday payrolls grade the next step
Chart analysis
Published chart · Tap chart to enlarge.
Published chart lesson
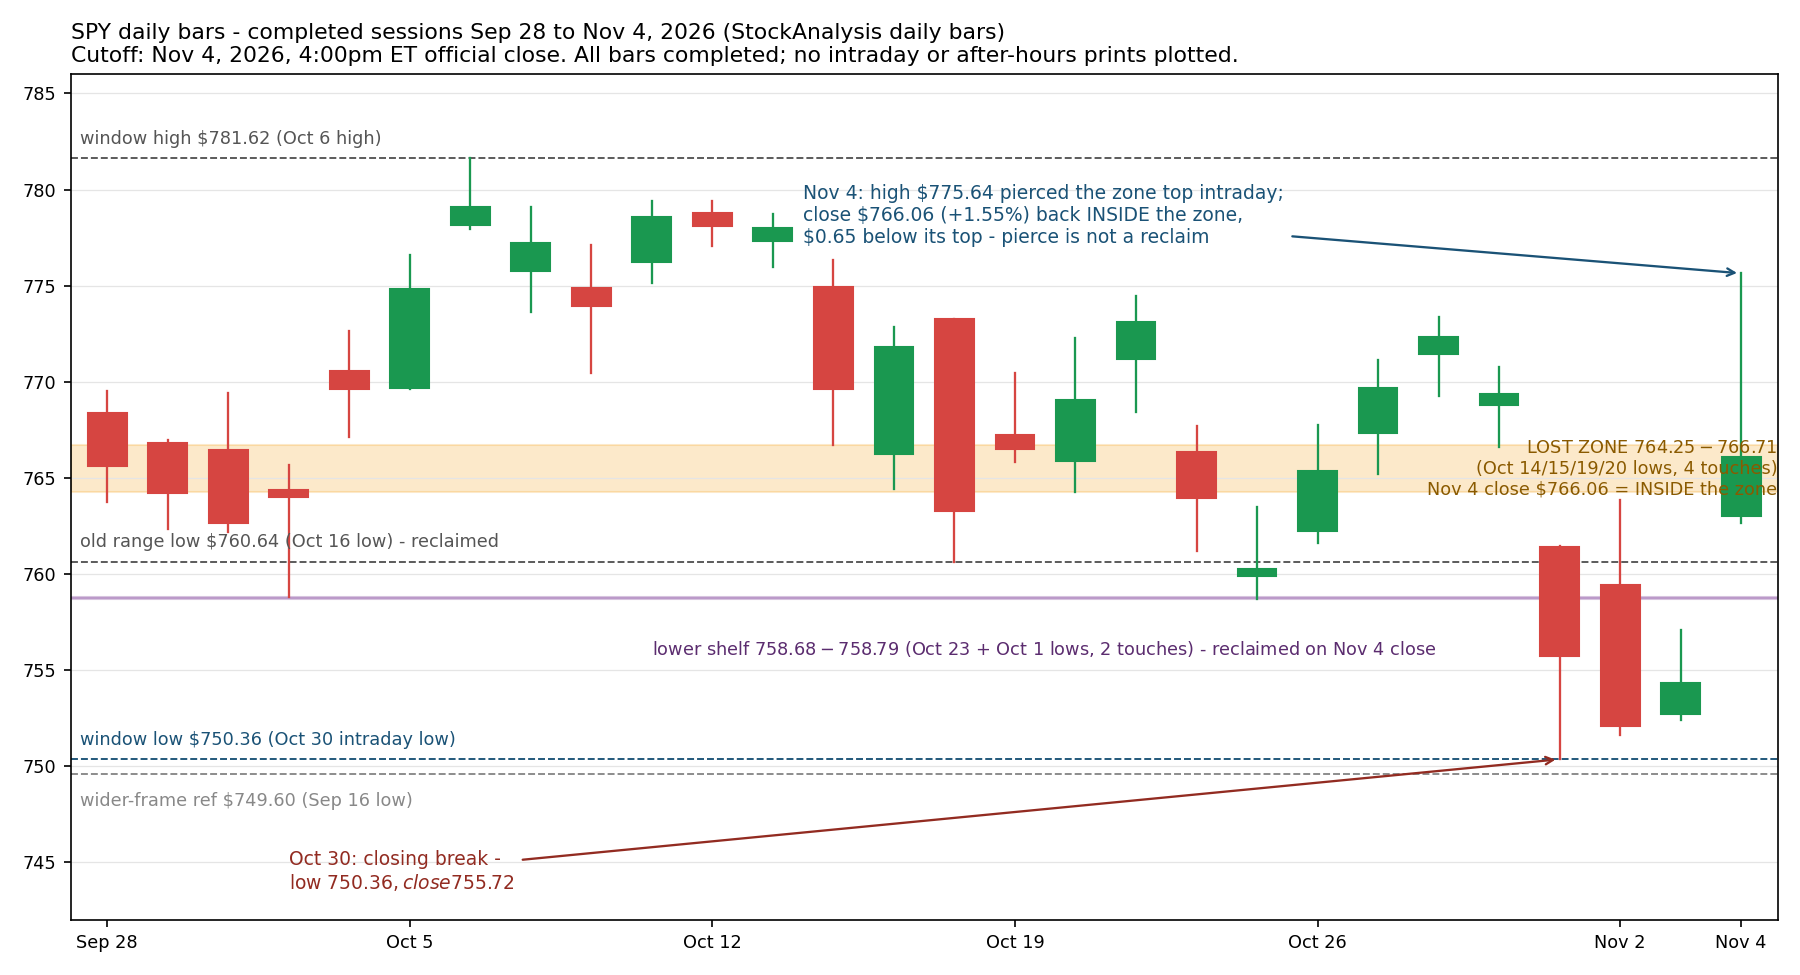
An intraday pierce of a lost zone is not a reclaim — the reclaim is graded on where the completed bar closes. SPY's lost zone is $764.25–$766.71, built from the Oct 14, Oct 15, Oct 19 and Oct 20 completed lows (StockAnalysis daily bars). Today the bar's high of $775.64 traded $8.93 above the zone top, but the completed close of $766.06 settled back inside the zone, $0.65 below its top — so on completed bars the shelf below ($758.68–$758.79) and the old range low ($760.64) are reclaimed, and the zone is not. The same bar can therefore pass one test and fail the next one up; grading each level on its own close keeps the two separate. What would weaken this lesson: a completed close above $766.71, followed by a retest of the zone from above that holds on a completed close, would grade the zone as reclaimed; a completed close back below $764.25, the zone bottom, would instead show today's close inside the zone was a visit, not a foothold.
Brief analysis source: SPY daily bars, StockAnalysis, Nov 4, 2026 (completed close, 4:00pm ET) . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- SPY reclaimed the shelf but not the zone: the completed close was $766.06, up 1.55% (StockAnalysis) — above the $758.68–$758.79 shelf and the $760.64 old range low, but inside the lost $764.25–$766.71 zone, $0.65 below its top, after the $775.64 high pierced it intraday.
- The rally was broad and coincided with yields easing: 371 S&P 500 members rose against 127 decliners (ChartRow, Nov 4 close), the Dow gained 3.0% (CNN), ADP payrolls beat at 86,000 (Reuters), ISM services printed 54.5 with prices paid at 73.0 (ISM), and Brent settled down almost 8.7% at $94.62 (CNN).
- Options learning point: a completed close above a shelf is graded repair step one, not a finished reclaim — the zone top at $766.71 (the Oct 14 low) still needs a completed close above it and a held retest, and with jobless claims Thursday and the October jobs report Friday, any premium sold must survive two more dated event prints, while waiting puts no option premium at risk.
Read the full brief and sources
- Start from the widest frame, on completed daily bars. SPY (the S&P 500 ETF) opened at $762.99, reached $775.64, fell to $762.64 and closed at $766.06, up 1.55% (StockAnalysis daily bars, completed bar), on 48.9 million shares — heavier than Tuesday's 32.9 million. The completed Sep 28–Nov 4 window still runs from $781.62 (the Oct 6 high) down to $750.36 (the Oct 30 intraday low), and today's close sits in its upper half without changing either boundary. The index closes behind it: the Dow surged 1,569 points, or 3.0% — its best day since April 2025 and its biggest single-day gain after a midterm election since 1982 (CFRA Research via CNN) — the S&P 500 index rose 1.58% and the Nasdaq Composite 1.44%, its biggest post-midterm gain since 2018 (CNN); the Russell 2000 was up 1.64% in midday trade (ad-hoc news). QQQ (the Nasdaq-100 ETF) opened at $688.43, reached $701.45, fell to $687.87 and closed at $693.05, up 1.13% (completed bar) — a smaller gain than the Dow's, because the chip and data-center names that led the autumn advance were the day's laggards.
- Grade the day against the test the morning brief set, on completed bars — the first step passed, the second did not. The morning's rule: repair is graded on a completed close above the $758.68–$758.79 shelf (the Oct 23 and Oct 1 lows, two touches), then the lost zone. Today's close of $766.06 cleared the shelf top by $7.27 and the old range low of $760.64 (the Oct 16 low) by $5.42, so the shelf and the old range low are reclaimed on a completed close — the first graded repair evidence of this break. But the high of $775.64 pierced the $764.25–$766.71 lost zone (built from the Oct 14, Oct 15, Oct 19 and Oct 20 lows, four touches) by $8.93 intraday and the close came back inside it, $0.65 below the zone top: an intraday pierce is not a reclaim, and the zone itself is not yet reclaimed on a completed close. A retest from above that holds is still ahead; nothing today graded it.
- Participation flipped from Tuesday's narrow tape, while the day's data stayed firm. At today's close 371 S&P 500 members rose against 127 that fell, with 66% of members above their 50-day average (327 of 498 eligible) and 61% above their 200-day average (ChartRow, Nov 4 close) — the mirror image of Tuesday's 185 advancers against 311 decliners, though the average-based shares barely moved, because one day lifts prices faster than it lifts the averages they are measured against. The morning's ADP report had already shown private payrolls up 86,000 against 69,000 expected (Reuters), and the ISM services index followed at 54.5 in October, just under the 54.7–54.8 consensus, with prices paid still high at 73.0 and employment up to 51.4 (ISM Services PMI report). The 10-year Treasury yield eased from Tuesday's 4.95% close to about 4.90% in afternoon trade while the VIX sank almost 20% (CNN) — the rally coincided with yields falling, not rising, for the first time in this break.
- The rest of the board moved with the election result and the oil slide, in one compressed pass. Brent crude settled down almost 8.7% at $94.62 a barrel, its lowest settle since August 31, after Vice President Vance tied the Republican losses to the war with Iran (CNN); WTI crude fell about 8% to near $88.50 a barrel in afternoon trade (Investor's Business Daily). Spot gold was quoted at $4,058.90 an ounce, up 3.31%, in mid-afternoon trade (Kitco), and bitcoin traded at $80,439 with ether at $2,430.75 around midday (Daily Market Report, 12:03pm ET snapshot). Among single stocks, CVS Health fell 12.5% after announcing it would split into two companies (CNN), Nvidia fell 3% and CoreWeave sank roughly 10% as data-center names were sold (CNN), while ExxonMobil fell 5.3% and ConocoPhillips 5.9% in the afternoon alongside crude (Associated Press).
- Tonight's earnings are a separate, later development — they did not decide today's 4:00pm ET close, and their first full-session grade comes tomorrow. Qualcomm beat on both lines for its fiscal fourth quarter — adjusted EPS of $2.17 against $2.16 expected and revenue of about $10.4 billion against about $10.1 billion expected — but its shares slipped about 2% after hours as its profit guidance came in light (InvestingLive). Verified from the official releases: Aflac reported GAAP diluted EPS of $0.61 and adjusted earnings per diluted share of $2.43 on total revenues of $3,271 million (PR Newswire), and Expedia reported GAAP diluted EPS of $8.42 and adjusted EPS of $9.39 on revenue of $4,938 million (Business Wire). Arm, AppLovin and MercadoLibre were still to come later this evening at this check. A question to study, not a trade: the close reclaimed the shelf but stopped inside the zone, on a day when the Dow led and the chip leaders lagged — what would tomorrow's completed close, and Friday's jobs report, need to show for today's step to count as repair in progress rather than a one-day election repricing that stalls at the zone top?
Analyst interpretation: today earned a genuinely different grade from Monday and Tuesday — the shelf and the old range low were reclaimed on a completed close, with broad participation (ChartRow) and heavier volume than Tuesday (StockAnalysis). What it did not earn is the zone: the intraday push ran $8.93 through the zone top and the close fell back inside it, and the day's leadership was the Dow and the broad tape, not the chip names whose break started this move. One close is a narrow pass, and this one arrives directly in front of the week's two biggest remaining prints — jobless claims on Thursday and the October jobs report on Friday — with the 10-year yield still near 4.90% and December hike pricing at 76.9% this morning (CME FedWatch, Nov 4). A hypothetical teaching example only — not a market quote and not a trade: in the Options Industry Council's terms, a put credit spread sells one put and buys a lower-strike put with the same expiry; sold for a hypothetical $1.25 credit on a $5-wide spread, its maximum gain is $1.25, its maximum loss is $3.75 plus fees, and its breakeven is the short strike minus $1.25. If the underlying expires between the strikes with the spread worth $2.75, the loss is $1.50 before fees — the full $3.75 is lost only at or below the long strike — and the short put carries assignment risk before expiry. A larger credit is not a higher win rate; the breakeven condition is what has to hold. Waiting puts no option premium at risk; its cost is possibly missing a further move, not a spread loss. Step one of repair is on the board; the zone test and two event prints are still ahead, so patience remains a valid position.
A completed close back below $764.25, the bottom of the lost zone (the Oct 20 low), would confirm the break is reasserting itself and grade today's close inside the zone as a visit that failed. A completed close below $760.64, the Oct 16 low (the old range low reclaimed today), and then below $758.68, the shelf bottom (the Oct 23 low), would confirm the repair step itself has failed.
A completed close above $766.71, the zone top (the Oct 14 low), would be the second step of repair — the zone reclaimed on a close, a narrow pass on its own — and a later retest of $764.25–$766.71 from above that holds on a completed close would be stronger evidence the Oct 30 break is over. Above the zone, the next shelves are the completed lows at $769.24 (Oct 28) and $770.44 (Oct 8), which is where a further advance would be graded next.
A position was closed and a new position was opened today, per confirmed fills recorded in the activity log.
Sources
- SPY daily bars (open/high/low/close) and volume — StockAnalysisNov 4, 2026, 4:00pm ET close (completed bars through Nov 4)
- QQQ daily bars (open/high/low/close) — StockAnalysisNov 4, 2026, 4:00pm ET close (completed bars through Nov 4)
- Closing wrap: Dow +1,569 points (+3.0%), best day since April 2025 and biggest post-midterm gain since 1982 (CFRA); S&P 500 +1.58%; Nasdaq Composite +1.44%; Brent settled -8.7% at $94.62, lowest since Aug 31; VIX sank almost 20%; CVS -12.5% on split plan; Nvidia -3%, CoreWeave about -10% — CNNNov 4, 2026, after the close
- Russell 2000 up 1.64% to 2,858.52 in midday trading; session range to 2,875.14 — ad-hoc newsNov 4, 2026, midday ET (intraday, not a close)
- S&P 500 breadth at the Nov 4 close: 371 advancers / 127 decliners; 66% of members above their 50-day average (327 of 498 eligible), 61% above their 200-day average (304 of 496 eligible) — ChartRowNov 4, 2026, 4:00pm ET
- ADP National Employment Report: October private payrolls +86,000 vs 69,000 expected (Reuters poll); September revised to +86,000 — ReutersNov 4, 2026, 8:15am ET release
- ISM Services PMI October 2026: 54.5% (September 54.9%); Business Activity 53.8%, New Orders 55.9%, Employment 51.4%, Prices 73.0% — ISM via PR NewswireNov 4, 2026, 10:00am ET release
- WTI crude fell about 8% to $88.50 a barrel; 10-year Treasury yield hit as low as 4.89% intraday — Investor’s Business Daily live coverageNov 4, 2026, afternoon ET
- 10-year Treasury yield fell about 6 basis points to 4.90% (Benzinga snapshot); gold spot $4,058.90 an ounce, +3.31% at 3:45pm (Kitco) — Eurasia Business News market wrapNov 4, 2026, afternoon ET (intraday snapshots, not settlements)
- Bitcoin $80,439 (+4.01%) and ether $2,430.75 (+6.99%) — Daily Market Report snapshotNov 4, 2026, 12:03pm ET snapshot
- ExxonMobil -5.3% and ConocoPhillips -5.9% in afternoon trade; HCA Healthcare +9.6%, Dollar Tree +8.9%, First Solar +5.8% — Associated Press afternoon reportNov 4, 2026, about 2:06pm ET (Associated Press snapshot)
- Qualcomm fiscal Q4: adjusted EPS $2.17 vs $2.16 consensus, revenue about $10.4B vs about $10.1B expected; shares slipped about 2% after hours on light profit guidance — InvestingLiveNov 4, 2026, 4:12pm ET
- Aflac Q3 2026: GAAP diluted EPS $0.61, adjusted earnings per diluted share $2.43, total revenues $3,271M — PR Newswire (official release)Nov 4, 2026, after the close
- Expedia Group Q3 2026: GAAP diluted EPS $8.42, adjusted EPS $9.39, revenue $4,938M — Business Wire (official release)Nov 4, 2026, after the close