
Daily brief · 2026-11-03
Historical edition · New York time. These observations reflect their published date, not current market conditions.
The bounce failed under the zone — Election Day opens with the break still in force
break un-repaired: second day under the lost zone, futures mixed, 10-year near 4.93% — election results tonight, payrolls Friday
Chart analysis
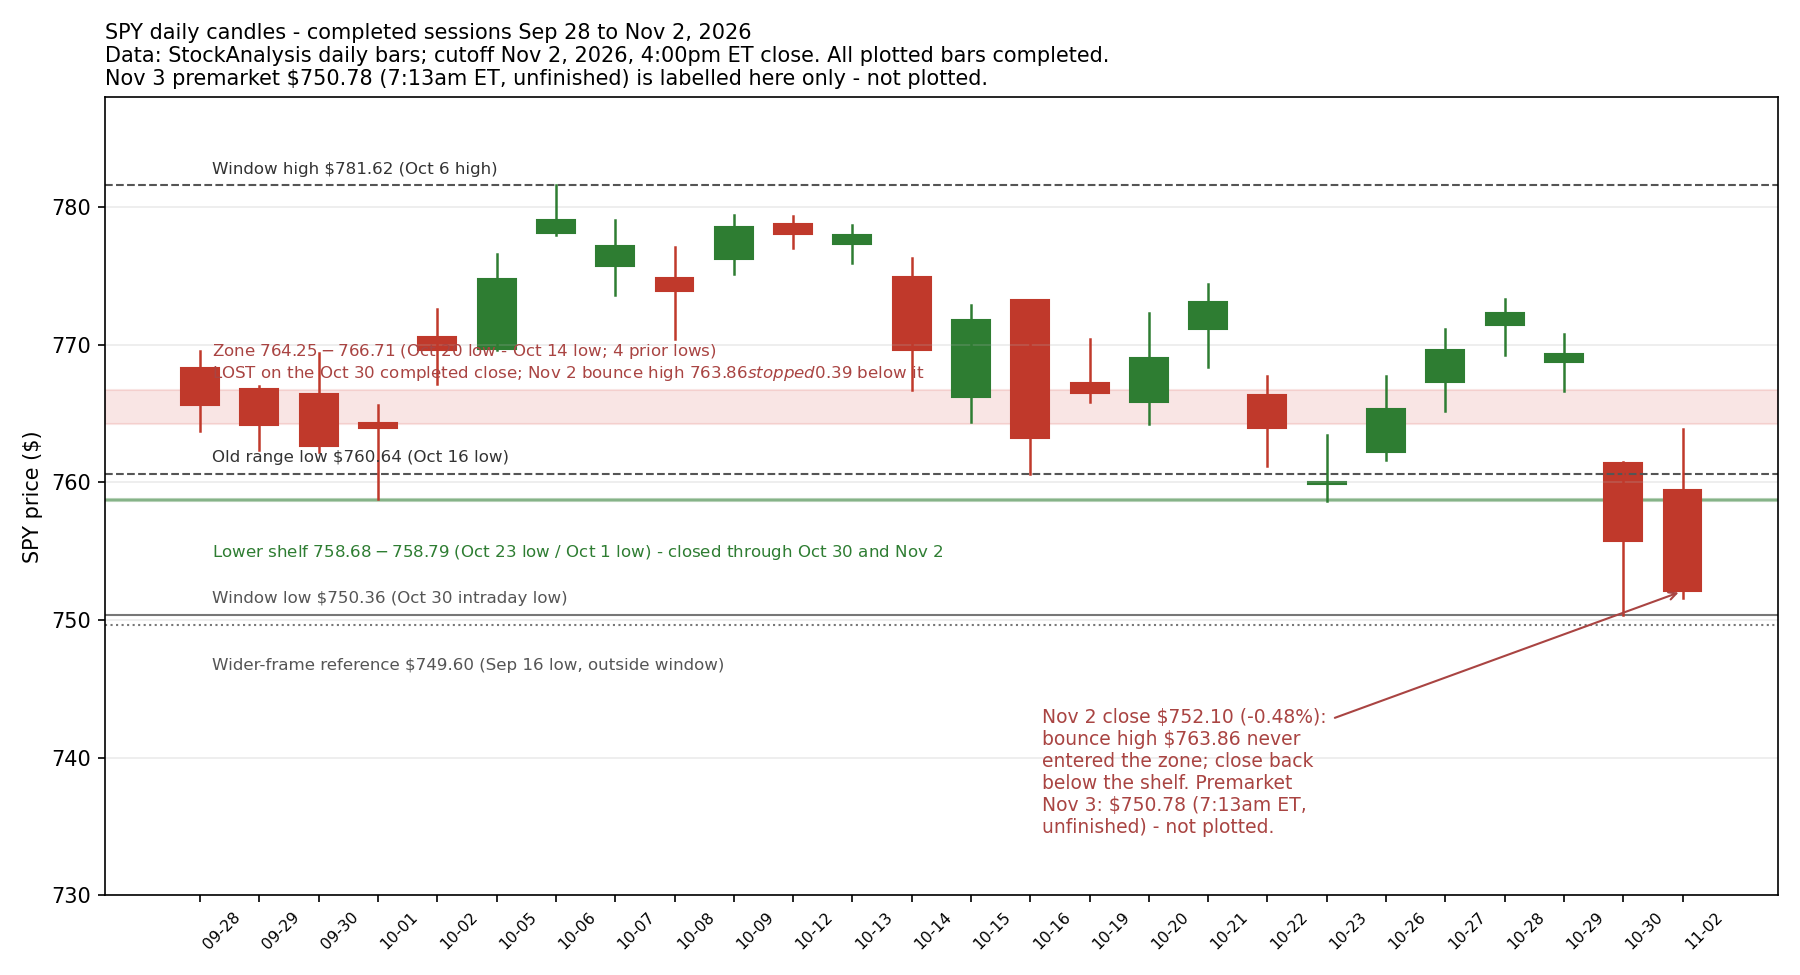
Published chart · Tap chart to enlarge.
Published chart lesson
A failed retest attempt is itself information: when a bounce stops just below a lost zone's underside and the bar closes back under the next shelf down, the break stays in force and the attempt shows where sellers are waiting. SPY's $764.25–$766.71 zone is built from four prior completed lows (StockAnalysis daily bars). Monday's completed bar reached $763.86 — $0.39 below the zone's bottom — and closed at $752.10, below the $758.68–$758.79 lower shelf, so on completed bars nothing was reclaimed. This morning's premarket print of $750.78 (7:13am ET, unfinished) sits $0.42 above the window low of $750.36 (Friday's intraday low) — proximity to a low is an observation, not established support. What would weaken the lesson: a completed close back above $766.71, the zone top, followed by a retest of the zone from above that holds, would grade the break as false; a completed close below $749.60, the Sep 16 low, would instead extend the break to the wider frame.
Brief analysis source: SPY daily bars, StockAnalysis, Nov 2, 2026 (completed close); premarket print Nov 3, 2026, 7:13am ET (unfinished) . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- Monday's bounce failed its test on completed bars: SPY's high of $763.86 stopped $0.39 below the lost $764.25–$766.71 zone and the close of $752.10 (down 0.48%, StockAnalysis) finished back below the $758.68–$758.79 shelf — the break is in force for a second close, with premarket at $750.78 (7:13am ET, unfinished) just $0.42 above the window low of $750.36.
- It is Election Day with no 8:30am ET release: the data test is JOLTS and factory orders at 10:00am ET, AMD reports after tonight's close, December hike pricing firmed to 74.9% (CME FedWatch, Nov 3), and Friday's October jobs report is the week's main print.
- Options learning point: a failed retest — a bounce that stops below a lost zone and closes back under the shelf — is graded evidence, not a bargain signal; with election results, ADP, jobless claims and payrolls all dated this week, any premium sold must survive four more event prints, while waiting puts no option premium at risk.
Read the full brief and sources
- Start with the widest frame, on completed daily bars. SPY (the S&P 500 ETF) on Monday opened at $759.45, reached $763.86, fell to $751.60 and closed at $752.10, down 0.48% (StockAnalysis daily bars, completed bar) — a second straight close below every shelf the autumn window built. The completed Sep 28–Nov 2 window runs from $781.62 (the Oct 6 high) down to $750.36 (Friday's intraday low), so Monday's close sits about 3.8% below the window high and in its lower reaches. The S&P 500 index itself closed at 7,541.40, down 0.51% (Reuters). QQQ (the Nasdaq-100 ETF) opened at $695.32, reached $699.43, fell to $680.33 and closed at $681.09, down 1.36% (completed bar) — a new closing low for the move, and Reuters notes the Nasdaq-100 index closed Monday more than 10% below its all-time closing high, a correction on that measure. The growth end is falling faster than the broad index for a third straight session.
- Inside that frame, Monday's bounce was graded — and it failed the test the premarket brief set. The $764.25–$766.71 zone, built from four prior completed lows (Oct 14 at $766.71, Oct 15 at $764.43, Oct 19 at $765.82, Oct 20 at $764.25), was never even entered intraday: the day's high of $763.86 stopped $0.39 below its bottom. The completed close of $752.10 finished below the $760.64 old range low (the Oct 16 low) and below the thin lower shelf at $758.68–$758.79 (the Oct 23 and Oct 1 lows, two touches), so Friday's closing break stays in force, now with a failed retest attempt on top of it. This morning SPY traded at $750.78 in premarket at 7:13am ET, down 0.18% (StockAnalysis, unfinished) — $0.42 above the window's $750.36 intraday low, with $749.60 (the Sep 16 low, a wider-frame reference from before this window) just below that. QQQ traded at $682.22 at 7:00am ET, up 0.17% (unfinished). Index futures were mixed: S&P 500 futures down about 0.1%, Dow futures down about 0.8% and Nasdaq-100 futures up about 0.3% (Dow Jones Newswires via Morningstar, 8:11am ET update). A mixed premarket grades nothing; today's completed close — back above the shelf, still below it, or through $750.36 — is the evidence.
- There is no 8:30am ET release today — the site's economic calendar is empty at that slot — so today's scheduled data test comes at 10:00am ET: September job openings (JOLTS) and factory orders. JOLTS is expected to show openings near 7.10 million, little changed from August's 7.079 million (CNBC, via TradersUnion). The 10-year Treasury yield traded around 4.925%, up about 3 basis points (Dow Jones Newswires via Morningstar), with Investopedia putting it at 4.936% — high and steady, not easing. December rate pricing firmed: CME FedWatch as of Nov 3 put a 25bp hike at the Dec 9 meeting at 74.9% (Cointime reading of CME FedWatch), up from 69.8% on Nov 1 — the market is leaning harder into a hike just as price structure weakens. Under the surface, participation told a different story from the cap-weighted index: 345 S&P 500 members rose and 154 fell on Monday, with 67% of members above their 50-day average (334 of 498 eligible) and 63% above their 200-day average at the Nov 2 close (ChartRow) — the index fell because its largest technology names fell, not because most stocks did. That split is a fact about Monday; whether it steadies the index or the index drags the rest down is what the next closes grade.
- Overnight, the chip selling spread through Asia while the US voted. South Korea's Kospi fell about 4.1% and Taiwan's benchmark fell 3.3%, while the Hang Seng added 0.2% and Japan's markets were closed for the Culture Day holiday (Reuters). European futures pointed lower in early trade (Reuters). Oil steadied after Monday's steep fall: Brent crude was up 0.5% at $105.30 a barrel in Asian trading (Reuters) and US crude traded near $97.40, up about 1% (TalkMarkets). Gold was softer, near $3,920 an ounce, and bitcoin was little changed around $76,800 (Reuters; TalkMarkets). Last night's two big reports get their first full-session grade today: Apple fell 4.5% in premarket trading after warning that rising memory-chip costs will pressure its holiday-quarter gross margin (Reuters), and Palantir also traded lower premarket despite reporting revenue well above its own guidance. Retail sentiment is context only: the AAII survey for the week ended Oct 28 (bullish 37.8%, bearish 41.4%) was measured before the break, so it cannot describe how investors feel after it.
- This morning's BMO earnings, verified from official releases: Pfizer reported reported diluted EPS of $0.56 and adjusted diluted EPS of $0.87 on revenues of $16,583 million and raised its full-year guidance (Business Wire). Shopify reported GAAP diluted EPS of $0.36 and non-GAAP diluted EPS of $0.49 on revenue of $3,742 million, up 32% (GlobeNewswire) — and still fell about 16% in premarket trading (Swingfolio morning snapshot, 7:36am ET): a beat against estimates is not the same as a beat against what the price already assumed. Eaton reported EPS of $2.77 and adjusted EPS of $3.68 on net sales of $8,947 million (Business Wire); Marathon Petroleum reported $26.59 per diluted share and adjusted $26.93 (PR Newswire); Yum! Brands reported GAAP EPS of $5.92 — lifted by an approximately $1.7 billion pre-tax gain on the completed Pizza Hut divestitures — and EPS excluding special items of $1.56 (Business Wire); Gartner reported GAAP diluted EPS of $3.35 and adjusted EPS of $3.59 (Business Wire); Waters reported GAAP diluted EPS of $0.82 against adjusted EPS of $4.10 (PR Newswire); DuPont reported GAAP EPS from continuing operations of $1.24 and adjusted EPS of $2.09 (PR Newswire); Ball reported a GAAP diluted loss of $0.36 per share against comparable diluted EPS of $1.10 (PR Newswire). Kept on the reconciliation queue rather than recorded: Apollo, Teva and Keurig Dr Pepper, whose GAAP figures could not be verified from the official release text in this check, and Cinemark, whose wire release carried no EPS figure. A question to study, not a trade: Shopify beat and fell about 16% premarket while the index's break is so far a large-cap technology story — what would today's completed closes in the growth names need to show for results like these to count as repair, rather than as more evidence of how much was already priced in?
Analyst interpretation: the chart's grade did not change on Monday — it was confirmed. A bounce that stops $0.39 short of a lost zone and closes back below the lower shelf says sellers are still active at the levels that used to be support, and this morning's mixed futures and $750.78 premarket print (unfinished) have not repaired any of it. The one counterweight is participation: most S&P 500 members rose on Monday even as the cap-weighted index fell (ChartRow, Nov 2 close), so this is so far a large-cap technology break, not yet a broad one — but that split resolves through completed closes, not through hope. The calendar argues for patience on its own: election results tonight, ADP on Wednesday, jobless claims on Thursday and the October jobs report on Friday, into a Dec 9 Fed meeting the market now prices at 74.9% for another hike (CME FedWatch, Nov 3). A hypothetical teaching example only — not a market quote and not a trade: in the Options Industry Council's terms, a put credit spread sells one put and buys a lower-strike put with the same expiry; sold for a hypothetical $1.60 credit on a $10-wide spread, its maximum gain is $1.60, its maximum loss is $8.40 plus fees, and its breakeven is the short strike minus $1.60. If the underlying expires between the strikes with the spread worth $5.00, the loss is $3.40 before fees — the full $8.40 is lost only at or below the long strike — and the short put carries assignment risk before expiry. A high credit is not a high win rate; the breakeven condition is what has to hold. Waiting puts no option premium at risk; its cost is possibly missing a further move, not a spread loss. With the break un-repaired and four event prints still ahead this week, waiting is a valid position.
A completed close below $750.36, Friday's intraday low and the bottom of the Sep 28–Nov 2 window, would confirm the break is extending rather than repairing — and a completed close below $749.60, the Sep 16 low that both Friday's and Monday's lows stopped above, would extend it to the wider frame. A rally that again stops below $764.25, the zone bottom (the Oct 20 low), and closes back under the $758.68–$758.79 shelf would add a second failed retest to the evidence.
A completed close back above $766.71, the zone top (the Oct 14 low), would grade the Oct 30 closing break as a probe that failed — a narrow pass on its own; a later retest of the $764.25–$766.71 zone from above that holds on a completed close would be stronger evidence the break is over. A completed close above $760.64, the Oct 16 low, without reaching the zone would be only a first step: it reclaims the old range low, not the zone.
Sources
- SPY daily bars (open/high/low/close) and Nov 3 premarket print $750.78 at 7:13am ET (unfinished) — StockAnalysisNov 2, 2026, 4:00pm ET close (completed bars through Nov 2); premarket Nov 3, 2026, 7:13am ET
- QQQ daily bars and Nov 3 premarket print $682.22 at 7:00am ET (unfinished) — StockAnalysisNov 2, 2026, 4:00pm ET close (completed bars through Nov 2); premarket Nov 3, 2026, 7:00am ET
- Futures at the 8:11am ET update: Dow futures -0.8%, S&P 500 futures -0.1%, Nasdaq futures +0.3%; 10-year Treasury yield up about 3bp to around 4.925% — Dow Jones Newswires via MorningstarNov 3, 2026, 8:11am ET
- S&P 500 index closed at 7,541.40, down 0.51%; Nasdaq-100 closed more than 10% below its all-time closing high; Apple -4.5% premarket on its margin warning; Asia: Kospi -4.1%, Taiwan -3.3%, Hang Seng +0.2%, Japan closed; Brent +0.5% at $105.30 in Asian trading; bitcoin $76,822, up 0.1% — ReutersNov 3, 2026 (Reuters, published 10:49 UTC)
- 10-year Treasury yield 4.936%; Apple down almost 4% premarket; Palantir among the morning's larger premarket decliners, down nearly 8% — InvestopediaNov 3, 2026, morning ET
- S&P 500 breadth at the Nov 2 close: 345 advancers / 154 decliners; 67% of members above their 50-day average (334 of 498 eligible), 63% above their 200-day average — ChartRowNov 2, 2026 close
- September JOLTS at 10:00am ET today: openings expected near 7.10 million vs 7.079 million in August (CNBC) — TradersUnionNov 3, 2026
- CME FedWatch as of Nov 3, 2026: 74.9% probability of a 25bp hike at the Dec 9, 2026 FOMC meeting, up from 69.8% on Nov 1 — Cointime (CME FedWatch)Nov 3, 2026
- AAII Sentiment Survey, week ended Oct 28, 2026: bullish 37.8%, bearish 41.4% — AAIIOct 29, 2026 (survey week ended Oct 28, 2026)
- Pfizer Q3 2026: reported diluted EPS $0.56, adjusted diluted EPS $0.87, revenues $16,583M; full-year guidance raised — Business Wire (official release)Nov 3, 2026
- Shopify Q3 2026: GAAP diluted EPS $0.36, non-GAAP diluted EPS $0.49, revenue $3,742M, up 32% — GlobeNewswire (official release, full text via Morningstar)Nov 3, 2026
- Shopify shares -16.18% in premarket trading — Swingfolio US pre-market snapshotNov 3, 2026, 7:36am ET
- Eaton Q3 2026: GAAP EPS $2.77, adjusted EPS $3.68, net sales $8,947M — Business Wire (official release)Nov 3, 2026
- Marathon Petroleum Q3 2026: $26.59 per diluted share, adjusted $26.93 — PR Newswire (official release)Nov 3, 2026
- Yum! Brands Q3 2026: GAAP EPS $5.92, EPS excluding Special Items $1.56, revenues $2,054M — Business Wire (official release)Nov 3, 2026
- Gartner Q3 2026: GAAP diluted EPS $3.35, adjusted EPS $3.59, revenues $1,505M — Business Wire (official release)Nov 3, 2026
- Waters Q3 2026: GAAP diluted EPS $0.82, adjusted EPS $4.10, revenue $1,767M — PR Newswire (official release)Nov 3, 2026
- DuPont Q3 2026: GAAP EPS from continuing operations $1.24, adjusted EPS $2.09, net sales $1,868M — PR Newswire (official release)Nov 3, 2026
- Ball Q3 2026: GAAP diluted loss per share -$0.36, comparable diluted EPS $1.10, net sales $4,188M — PR Newswire (official release)Nov 3, 2026
The low held, nothing was reclaimed — the break ends a third day in force
break in force, day three: low held on light volume, bounce stopped under the shelf — election night and Friday payrolls decide next
Chart analysis
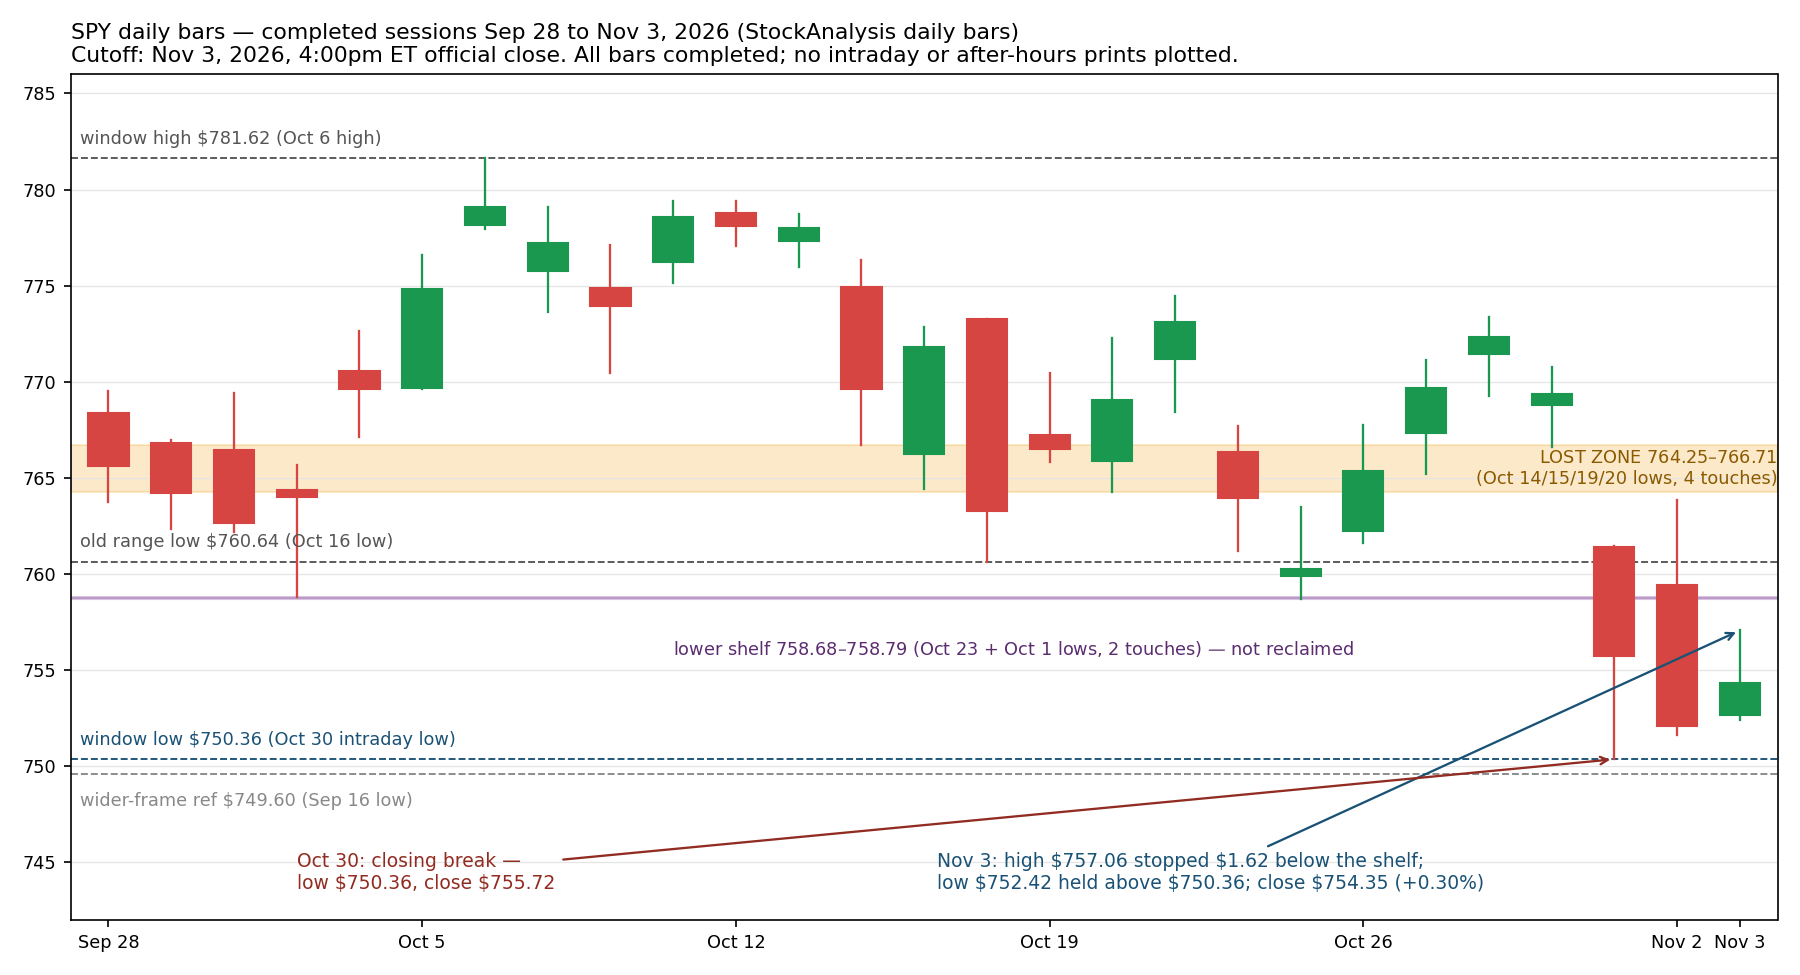
Published chart · Tap chart to enlarge.
Published chart lesson
A hold above a low is not a reclaim — the two are graded at different levels. Stopping the fall only requires buyers to appear above the low; repair requires completed closes back through the levels that were lost, starting with the nearest shelf. Today SPY (StockAnalysis daily bars) did only the first: its low of $752.42 held $2.06 above the $750.36 window low (the Oct 30 intraday low), while its high of $757.06 stopped $1.62 below the $758.68–$758.79 shelf built from the Oct 23 and Oct 1 lows, and the close of $754.35 stayed below that shelf, below the $760.64 old range low (the Oct 16 low) and below the $764.25–$766.71 lost zone. Nothing on the map moved. What would weaken this lesson: a completed close above $758.79, the shelf top, would be the first piece of repair evidence, and a completed close above $766.71, the zone top, followed by a retest from above that holds, would grade the break as false; a completed close below $750.36 would instead confirm the break is extending.
Brief analysis source: SPY daily bars, StockAnalysis, Nov 3, 2026 (completed close, 4:00pm ET) . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- SPY held above the window low without reclaiming anything: the completed close was $754.35, up 0.30% (StockAnalysis), with the low of $752.42 holding $2.06 above $750.36 (the Oct 30 low) and the high of $757.06 stopping $1.62 below the $758.68–$758.79 shelf — a third straight close below the lost $764.25–$766.71 zone.
- The bounce was narrow and came with rates rising: only 185 S&P 500 members rose against 311 decliners (ChartRow, Nov 3 close), September job openings beat expectations at 7.523 million (BLS), and the 10-year yield rose about 5 basis points to near 4.95% (Investor's Business Daily) — with tonight's election results and Friday's jobs report still ahead.
- Options learning point: a hold above a low is not a reclaim, and tonight's AMD-led earnings (GAAP diluted EPS $1.46, non-GAAP $2.09, revenue $13,377 million — GlobeNewswire) plus the election results are dated event risk that any premium sold today must survive; waiting puts no option premium at risk.
Read the full brief and sources
- Start from the widest frame, on completed daily bars. SPY (the S&P 500 ETF) opened at $752.68, reached $757.06, fell to $752.42 and closed at $754.35, up 0.30% (StockAnalysis daily bars, completed bar) — a third straight close in the lower reaches of the Sep 28–Nov 3 window, which runs from $781.62 (the Oct 6 high) down to $750.36 (the Oct 30 intraday low). The S&P 500 index closed at 7,568.96, up 27.56 points or 0.37%; the Nasdaq Composite rose 0.83% to 25,372.01; the Dow fell 0.38% to 51,786.15 and the Russell 2000 added 0.24% to 2,812.48 (eOption closing recap). The split was historic in a small way: Barron's notes the Nasdaq's gain was its best on a midterm Election Day since 2010, while the Dow's fall was its first on a midterm Election Day since 1990.
- Grade the day against the tests the morning brief set, on completed bars — neither trigger fired. On the downside, SPY's low of $752.42 held $2.06 above $750.36, the window low whose break on a completed close would have confirmed the move is extending, and $749.60 (the Sep 16 low) was never approached. On the upside, the bounce stopped early: the high of $757.06 finished $1.62 below the bottom of the thin lower shelf at $758.68–$758.79 (the Oct 23 and Oct 1 lows, two touches) and never reached the old range low of $760.64 (the Oct 16 low), let alone the lost $764.25–$766.71 zone built from four prior completed lows (Oct 14, Oct 15, Oct 19 and Oct 20). QQQ (the Nasdaq-100 ETF) told the same story one step stronger: it opened at $684.39, reached $688.69, fell to $683.18 — above Monday's $680.33 low — and closed at $685.28, up 0.62% (completed bar). Volume argues against reading much into the bounce: SPY traded 30.7 million shares, against 50.8 million on Monday and 77.7 million on Friday (StockAnalysis). A hold above the low is not a reclaim of anything above it.
- Under the surface, the bounce was narrower than the index suggests. Only 185 S&P 500 members rose against 311 that fell at today's close, with 67% of members above their 50-day average (334 of 498 eligible) and 63% above their 200-day average (ChartRow, Nov 3 close) — the cap-weighted index rose because its largest chip names rose while most stocks fell, the mirror image of Monday. The day's data leaned firm: September job openings rose to 7.523 million, above the roughly 7.10 million expected, with August revised up to 7.190 million (Bureau of Labor Statistics), and September factory orders rose 1.8% against a 1.3% estimate (CNBC). The 10-year Treasury yield rose about 5 basis points to close near 4.95% (Investor's Business Daily) — the bounce happened while yields rose, not because they fell, so the rate headwind flagged this morning is still in place into tonight's election results and Friday's jobs report.
- Chip stocks led what advance there was: Nvidia rose 2.2%, Broadcom 2.8% and AMD 4.2% into its after-close report (Associated Press), while Apple fell 1.9% and Palantir 1.6% (Wall Street Journal). Among the morning's reporters, Shopify closed down 8.7% after its merchandise volume of $119.1 billion fell short of the roughly $120 billion analysts expected (Barron's; Finnhub close), while DuPont closed up 8.6% and Revvity up 7.8% (Finnhub closes). Elsewhere, WTI crude was little changed near $96 a barrel in afternoon trade, after Monday's 7.4% settlement drop (Investopedia; Associated Press), gold futures fell about 1% to near $3,935 an ounce (Investopedia), and bitcoin traded at $77,527 with ether at $2,287 in the afternoon (Benzinga via TradingView).
- Tonight's earnings are a separate, later development — they did not decide today's 4:00pm ET close, and their first full-session grade comes tomorrow. Verified from the official releases: AMD reported GAAP diluted EPS of $1.46 and non-GAAP diluted EPS of $2.09 on revenue of $13,377 million (GlobeNewswire), and its shares rose in after-hours trading (Wall Street Journal). Amgen reported GAAP diluted EPS of $7.08 and non-GAAP diluted EPS of $6.45 on total revenues of $10,365 million (PR Newswire), and Arista Networks reported GAAP diluted EPS of $1.22 and non-GAAP diluted EPS of $1.20 on revenue of $3.66 billion (Business Wire). Super Micro's release also crossed after the close; Reuters reported revenue of $19.95 billion and adjusted EPS of $1.81 against a $1.23 estimate. Still to come later this evening: Duolingo's shareholder-letter figures, Suncor (scheduled 7:00pm ET), Itaú Unibanco and Ovintiv. Election results arrive tonight as polls close from 6:00pm ET, with index futures reopening at 6:00pm ET — the next session, not this close, prices them. A question to study, not a trade: the bounce arrived on the lightest volume of the three sessions and with most members falling — what would tomorrow's completed close need to show, in price and in participation, for today to count as the start of repair rather than a pause inside the break?
Analyst interpretation: today changed the least a day can change while still closing green. The break's map is identical to this morning's — zone lost, shelf unreclaimed, window low intact — and the one new fact cuts both ways: the low held, but on the lightest volume of the three sessions (SPY 30.7 million shares, StockAnalysis) and with most S&P 500 members falling (ChartRow). That is a pause with a narrow, chip-led bid, not evidence of repair; repair is graded on completed closes back through the levels above, not on a single up day under them. The calendar still argues for patience: election results tonight, ADP and the Treasury refunding on Wednesday, jobless claims on Thursday and the October jobs report on Friday, with the 10-year yield near 4.95% and December hike pricing at 74.9% this morning (CME FedWatch, Nov 3). A hypothetical teaching example only — not a market quote and not a trade: in the Options Industry Council's terms, a put credit spread sells one put and buys a lower-strike put with the same expiry; sold for a hypothetical $0.85 credit on a $5-wide spread, its maximum gain is $0.85, its maximum loss is $4.15 plus fees, and its breakeven is the short strike minus $0.85. If the underlying expires between the strikes with the spread worth $2.50, the loss is $1.65 before fees — the full $4.15 is lost only at or below the long strike — and the short put carries assignment risk before expiry. A larger credit is not a higher win rate; the breakeven condition is what has to hold. Waiting puts no option premium at risk; its cost is possibly missing a further move, not a spread loss. Mid-range inside a live break, with three event prints still ahead this week, waiting is a valid position.
A completed close below $750.36, the Oct 30 intraday low and the bottom of the Sep 28–Nov 3 window, would confirm the break is extending rather than pausing — and a completed close below $749.60, the Sep 16 low that Friday's, Monday's and today's lows all stopped above, would extend it to the wider frame. A second bounce that again stops below $758.68, the shelf bottom (the Oct 23 low), and closes back under today's $754.35 close would add another failed attempt to the evidence.
A completed close above $758.79, the shelf top (the Oct 1 low), would be the first step of repair — it reclaims the nearest shelf, not the lost zone. A completed close above $766.71, the zone top (the Oct 14 low), would grade the Oct 30 closing break as a probe that failed — a narrow pass on its own; a later retest of the $764.25–$766.71 zone from above that holds on a completed close would be stronger evidence the break is over.
A position was opened today, per a confirmed fill recorded in the activity log.
Sources
- SPY daily bars (open/high/low/close) and volume — StockAnalysisNov 3, 2026, 4:00pm ET close (completed bars through Nov 3)
- QQQ daily bars (open/high/low/close) — StockAnalysisNov 3, 2026, 4:00pm ET close (completed bars through Nov 3)
- Closing recap: Dow 51,786 (-197.83, -0.38%), S&P 500 7,568 (+27.56, +0.37%), Nasdaq 25,372 (+207.65, +0.83%), Russell 2000 2,812 (+6.60, +0.24%) — eOption Daily Market ReportNov 3, 2026 closing recap (after 4:00pm ET)
- Nasdaq's gain its best on a midterm Election Day since 2010; Dow's fall its first on a midterm Election Day since 1990 — Barron's closing cardNov 3, 2026, after the close
- S&P 500 breadth at the Nov 3 close: 185 advancers / 311 decliners; 67% of members above their 50-day average (334 of 498 eligible), 63% above their 200-day average — ChartRowNov 3, 2026, 4:00pm ET
- September JOLTS: job openings 7.523 million (August revised to 7.190 million), quits 3.365 million — Bureau of Labor Statistics (USDL-26-1630)Released Nov 3, 2026, 10:00am ET
- JOLTS reaction and the October jobs report outlook: Friday consensus +59,000, unemployment 4.2% (WSJ poll) — MarketWatchNov 3, 2026
- 10-year Treasury yield rose 5 basis points to 4.95% — Investor's Business Daily live coverageNov 3, 2026, near the close
- Nvidia +2.2%, Broadcom +2.8%, AMD +4.2% among the day’s strongest forces; most stocks in the index fell — Associated PressNov 3, 2026 (Associated Press closing wrap)
- Apple -1.9% and Palantir -1.6% at the close; AMD shares rose after hours on results that beat expectations — Wall Street Journal live coverageNov 3, 2026, after the close
- WTI crude down 0.5% to $96 in afternoon trade; gold futures down nearly 1% to $3,935 an ounce — InvestopediaNov 3, 2026, afternoon ET
- Shopify: merchandise volume $119.1 billion fell short of the roughly $120 billion expected — Barron'sNov 3, 2026
- Bitcoin $77,527 and ether $2,287, steady ahead of midterm results — Benzinga via TradingViewNov 3, 2026, 2:45pm ET
- AMD Q3 2026: GAAP diluted EPS $1.46, non-GAAP diluted EPS $2.09, revenue $13,377M — GlobeNewswire (official release)Nov 3, 2026, after the close
- Amgen Q3 2026: GAAP diluted EPS $7.08, non-GAAP diluted EPS $6.45, total revenues $10,365M — PR Newswire (official release)Nov 3, 2026, after the close
- Arista Networks Q3 2026: GAAP diluted EPS $1.22, non-GAAP diluted EPS $1.20, revenue $3.66B — Business Wire (official release, full text)Nov 3, 2026, after the close
- Super Micro Q1 FY2027: revenue $19.95B and adjusted EPS $1.81 vs $1.23 estimate (LSEG) — ReutersNov 3, 2026, after the close