
Daily brief · 2026-10-28
Historical edition · New York time. These observations reflect their published date, not current market conditions.
SPY closes above the $766.71 zone top — the $772.28 shelf and the Fed are today's tests
zone cleared on one close, shelf untested: SPY above $766.71 into a 2:00pm ET FOMC, 10-year at 5.01%, mega-cap earnings tonight
Chart analysis
Published chart · Tap chart to enlarge.
Published chart lesson
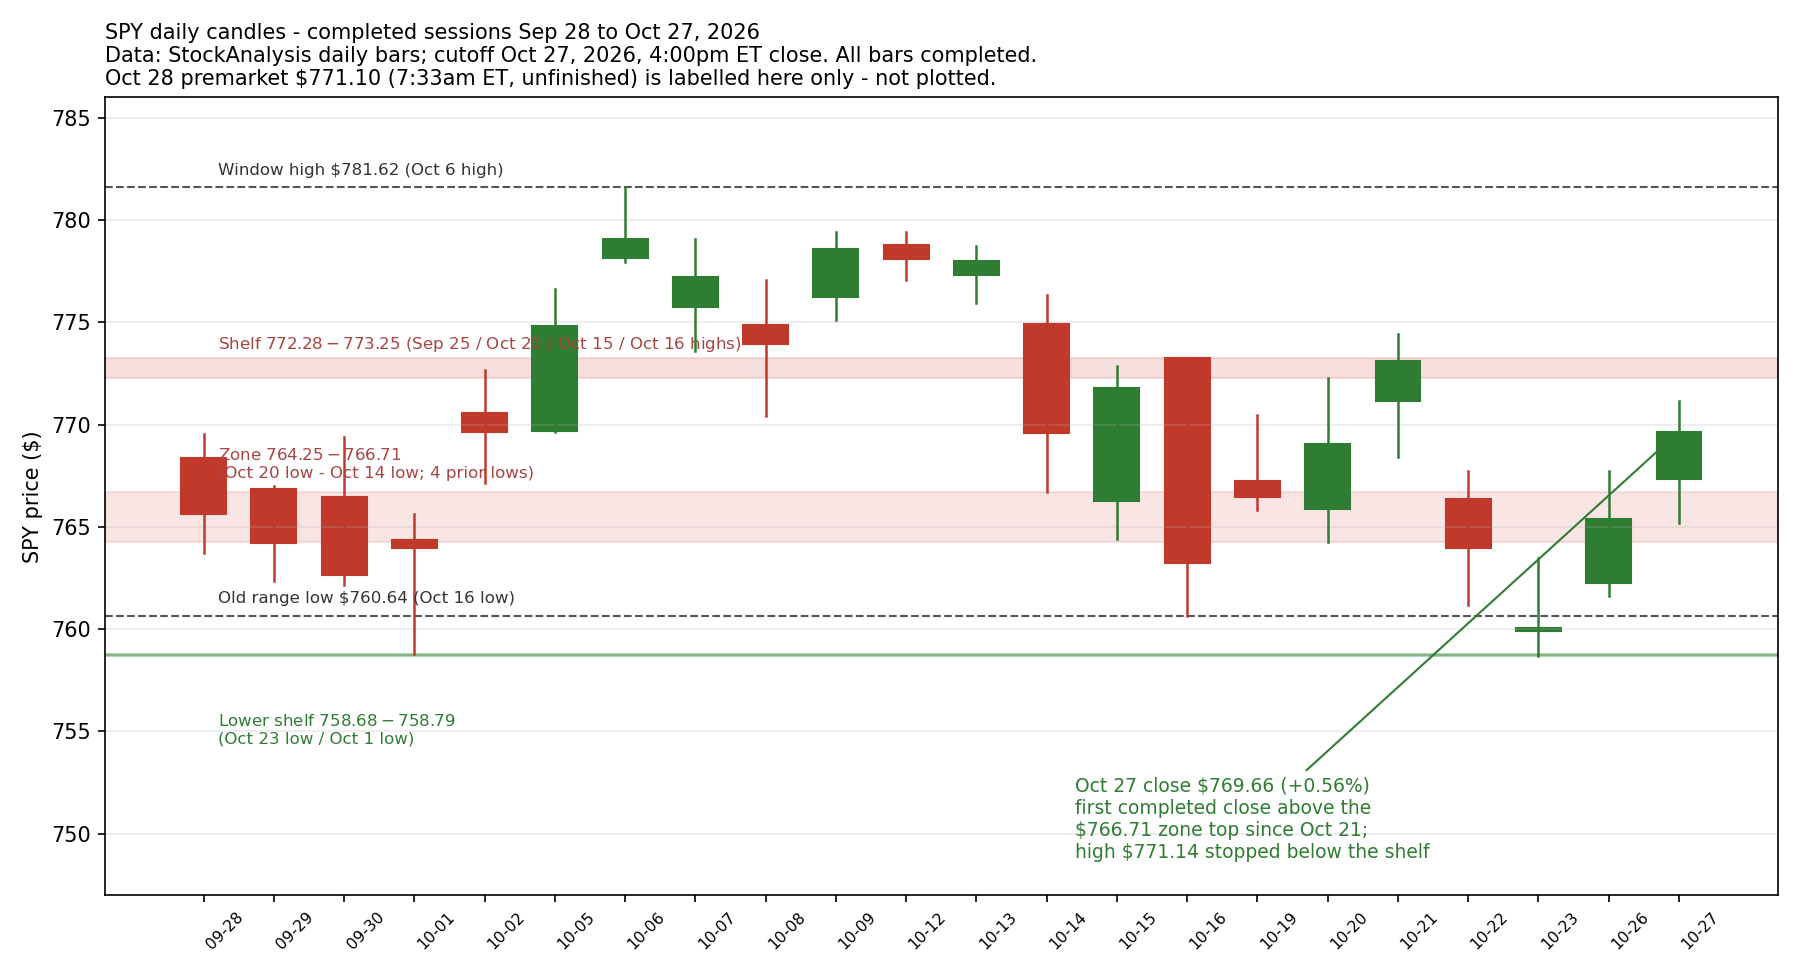
A close above a zone is a pass, not a finish: the grade improves only when a later test holds. SPY's $764.25-$766.71 zone is built from four prior completed lows (StockAnalysis daily bars): Tuesday's completed bar dipped to a $765.21 low inside the zone and closed at $769.66, above the $766.71 top (the Oct 14 low) — so the zone was tested intraday and held on a closing basis, which is one rung of evidence. The next rung would be a later session that dips toward the zone top and closes above it again; the rung above that is a completed close through the $772.28-$773.25 shelf. What would weaken the lesson: a completed close back below $766.71 would put the price inside the zone again and grade Tuesday's push above it as a false break in the other direction.
Brief analysis source: SPY daily bars, StockAnalysis, Oct 27, 2026 (completed close) . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- On completed bars, SPY closed Tuesday at $769.66, up 0.56% — the first completed close above the $764.25-$766.71 zone top ($766.71, the Oct 14 low, StockAnalysis) since Oct 21 — with the $772.28-$773.25 shelf (four prior highs) still untested above and Tuesday's high $1.14 below it.
- Today's scheduled test is the FOMC decision at 2:00pm ET (press conference 2:30pm ET): a hold at 3.75-4.00% is priced at about 91% (CME FedWatch via Reuters), the 10-year yield is 5.01%, and Alphabet and Microsoft report after today's close, before Thursday's 8:30am ET GDP and PCE releases.
- Options learning point: a close above a zone is one rung of evidence, not the whole ladder — a held retest grades stronger — and any premium sold today must survive three dated tests in about 24 hours (the FOMC, two mega-cap reports, then GDP and PCE), while waiting puts no option premium at risk.
Read the full brief and sources
- Start with the widest frame, on completed daily bars. SPY (the S&P 500 ETF) on Tuesday opened at $767.34, reached $771.14, held a low of $765.21 and closed at $769.66, up 0.56% (StockAnalysis daily bars) — the first completed close above $766.71, the Oct 14 low that sets the top of the $764.25-$766.71 zone, since the Oct 21 close, and $2.95 clear of it. Tuesday's low dipped into the zone and the close recovered above it, so the zone was tested intraday and held on a closing basis; a separate later session has not retested it yet. The wider Sep 28-Oct 27 completed window still runs from $781.62 (the Oct 6 high) down to $758.68 (the Oct 23 low), so Tuesday's close sits 1.5% below the window high — a repair inside a wider range, not a new high. The last completed week (Oct 19-23) closed at $759.97 near its low; this week's two completed bars have taken back the zone, nothing more yet.
- Inside that frame, the next test is directly overhead and it has not been touched on a closing basis. The $772.28-$773.25 shelf is built from four prior highs — the Sep 25 high ($772.28), the Oct 20 high ($772.29), the Oct 15 high ($772.87) and the Oct 16 high ($773.25) — and Tuesday's high of $771.14 stopped $1.14 below its bottom. Below the close, the first support area is the zone just cleared, $764.25-$766.71 (four prior lows: Oct 20, Oct 15, Oct 19 and Oct 14), then the old Oct 12-22 reference-range low at $760.64 (the Oct 16 low), then the thin lower shelf at $758.68-$758.79 (the Oct 23 and Oct 1 lows, two touches). QQQ (the Nasdaq-100 ETF) again closed stronger than SPY: open $715.12, high $722.87, low $713.59, close $721.25, up 1.27% (completed bar) — tech is leading the repair into today's reports.
- There is no 8:30am ET release today; the day's scheduled test is the FOMC decision at 2:00pm ET, with the press conference at 2:30pm ET. A hold at 3.75-4.00% is priced at about 91% (CME FedWatch via Reuters, Oct 28), which leaves about 9% for a hike — the same reading stored on Oct 26 — so the words around the decision, and any signal about December, matter more than the decision itself. This morning's unfinished prints are mixed and grade nothing: S&P 500 futures were up 0.20% and Nasdaq-100 futures up 0.44% while Dow futures were down 0.10% at 8:21am ET (TipRanks), SPY traded at $771.10 in premarket at 7:33am ET, up 0.19% (StockAnalysis, unfinished) — between Tuesday's close and the shelf, where only a completed close can grade the test — and the 10-year Treasury yield ticked up to 5.01% (Investopedia). Today's 4:00pm ET close grades today's tests; Alphabet and Microsoft report after that close, so their results are a separate, later piece of evidence, not part of today's closing grade.
- Participation on Tuesday was narrower than the index gains suggest, and the overnight picture is two-sided. Only five of the S&P 500's 11 sectors closed higher on Tuesday even as the index rose 0.60% to 7,722.60 — technology (XLK) rose 1.7% while energy (XLE) fell 2.1% — although advancing issues still beat decliners 1.83-to-1 on the NYSE (Zacks). The latest sourced S&P 500 breadth reading available at this check is Monday's: 60.8% of members above their 50-day average (Market Scholars, Oct 26); Tuesday's updated figure had not been published by the 8:45am ET check, so it is not claimed here. Overnight, Japan rose 1.1%, Hong Kong 0.2% and China 0.9% while India fell 0.5%, and Europe was slightly lower at midday (Seeking Alpha, 6:30am ET snapshot); in that same snapshot WTI crude futures were up 1.8% at $101.65, gold futures down 0.3% to $4,060.60 and bitcoin up 2.4% to $81,430, with the 10-year yield unchanged at 5.01%. Memory chips were a bright spot after SK Hynix's record quarter (Reuters via TipRanks), a read-through question for tonight's big-tech reports rather than a conclusion.
- This morning's BMO earnings, verified from official releases, were led by the AI-power names. GE Vernova reported diluted EPS of $4.81 on revenue of $12.6 billion, up 27%, with orders of $29 billion and full-year guidance raised (GE Vernova investor relations release). Vertiv reported diluted EPS of $1.95 and adjusted diluted EPS of $2.21 on net sales of $4,313 million, up 61%, with organic orders growth over 100% and full-year guidance raised across all key metrics (PR Newswire). Amphenol reported GAAP diluted EPS of $0.79 and adjusted diluted EPS of $0.80 on record net sales of $10,229.7 million, up 65% (Business Wire). Labcorp reported GAAP diluted EPS of $3.22 and adjusted EPS of $4.78 on revenue of $3.81 billion and raised its full-year guide (PR Newswire); Boston Scientific reported GAAP EPS of $0.40 and adjusted EPS of $0.73 on net sales of $5.138 billion (PR Newswire). UBS reported diluted EPS of $0.85 on total revenue of $13,352 million (UBS results release), and UMC reported earnings per ADS of US$0.206 (NT$1.32 per share) on revenue of NT$74.24 billion (Business Wire). Not every name is settled: ADP's wire alert points to its investor site and an SEC filing for the figures, and Biogen's release text could not be located at this check, so both stay unverified on the reconciliation queue rather than guessed, alongside the rest of today's BMO slate still being worked. Tonight's after-close reports from Alphabet and Microsoft (calls at 4:30pm and 5:30pm ET) are the next test of whether AI spending is converting into cloud revenue. A question to study, not a trade: do this morning's power-and-cooling beats widen beyond the data-center supply chain once Alphabet and Microsoft report their own capital spending tonight?
Analyst interpretation: Tuesday's close did the work Monday's could not — it finished above the zone instead of inside it — but grading stays honest: one close above is a narrow pass, the dip into the zone was intraday rather than a separate session's retest, and the $772.28-$773.25 shelf has not been tested on a closing basis at all. The cautious side is the calendar, not the chart: a 2:00pm ET FOMC decision with a possible December signal, Alphabet and Microsoft after the close, and GDP with PCE at 8:30am ET tomorrow, all with the 10-year yield back above 5%. Through a conservative put-seller's lens, that is three dated event tests inside roughly 24 hours. A hypothetical teaching example only — not a market quote and not a trade: a $10-wide put credit spread (sell one put, buy a lower-strike put with the same expiry, in the Options Industry Council's definition) sold for a hypothetical $2.60 credit has a maximum gain of $2.60, a maximum loss of $7.40 plus fees, and a breakeven at the short strike minus $2.60. If the underlying finishes between the strikes at expiry with the spread worth $5.00, the loss is $2.40 before fees — the full $7.40 is lost only at or below the long strike — and the short put carries assignment risk before expiry. Waiting puts no option premium at risk; its cost is possibly missing a further move, not a spread loss. With the shelf untested and the events stacked, waiting is a valid position.
A completed close above $773.25, the top of the $772.28-$773.25 shelf (the Oct 16 high), would show Tuesday's zone-clearing close had follow-through into the next shelf; separately, a later session that dips toward the $766.71 zone top (the Oct 14 low) and closes above it would grade the retest of the cleared zone as held — stronger evidence than the clearing close itself.
A completed close back below $766.71, the zone top (the Oct 14 low), would put SPY inside the $764.25-$766.71 zone again and grade Tuesday's push above it as a false break in the other direction; a completed close below $764.25, the zone bottom (the Oct 20 low), would reopen the $760.64 old range low (the Oct 16 low) as the next test.
Sources
- SPY daily bars (open/high/low/close) — StockAnalysisOct 27, 2026, 4:00pm ET close (completed bars through Oct 27)
- Index futures at 8:21am ET and Tuesday index closes — TipRanksOct 28, 2026, 8:21am ET
- Premarket snapshot: futures, 10-year yield at 5.01%, oil, gold, bitcoin — InvestopediaOct 28, 2026, morning ET
- CME FedWatch hold probability (91%) and dollar — ReutersOct 28, 2026
- Asia/Europe snapshot and 6:30am ET futures, oil, gold, bitcoin — Seeking AlphaOct 28, 2026, 6:30am ET snapshot
- Tuesday sector breadth (5 of 11 sectors higher, XLK +1.7%, XLE -2.1%, NYSE advancers 1.83-to-1) — ZacksOct 27, 2026 close
- GE Vernova Q3 2026 results release — GE Vernova investor relationsOct 28, 2026
- Vertiv Q3 2026 results release — PR NewswireOct 28, 2026
- Amphenol Q3 2026 results release — Business WireOct 28, 2026
- Labcorp Q3 2026 results release — PR NewswireOct 28, 2026
SPY pokes above the shelf, closes inside it at $772.31 — big tech splits after hours
shelf probed, not cleared: SPY closes inside $772.28-$773.25, the Fed holds 10-2, the 10-year nears 5.04%, GDP and PCE tomorrow
Chart analysis
Published chart · Tap chart to enlarge.
Published chart lesson
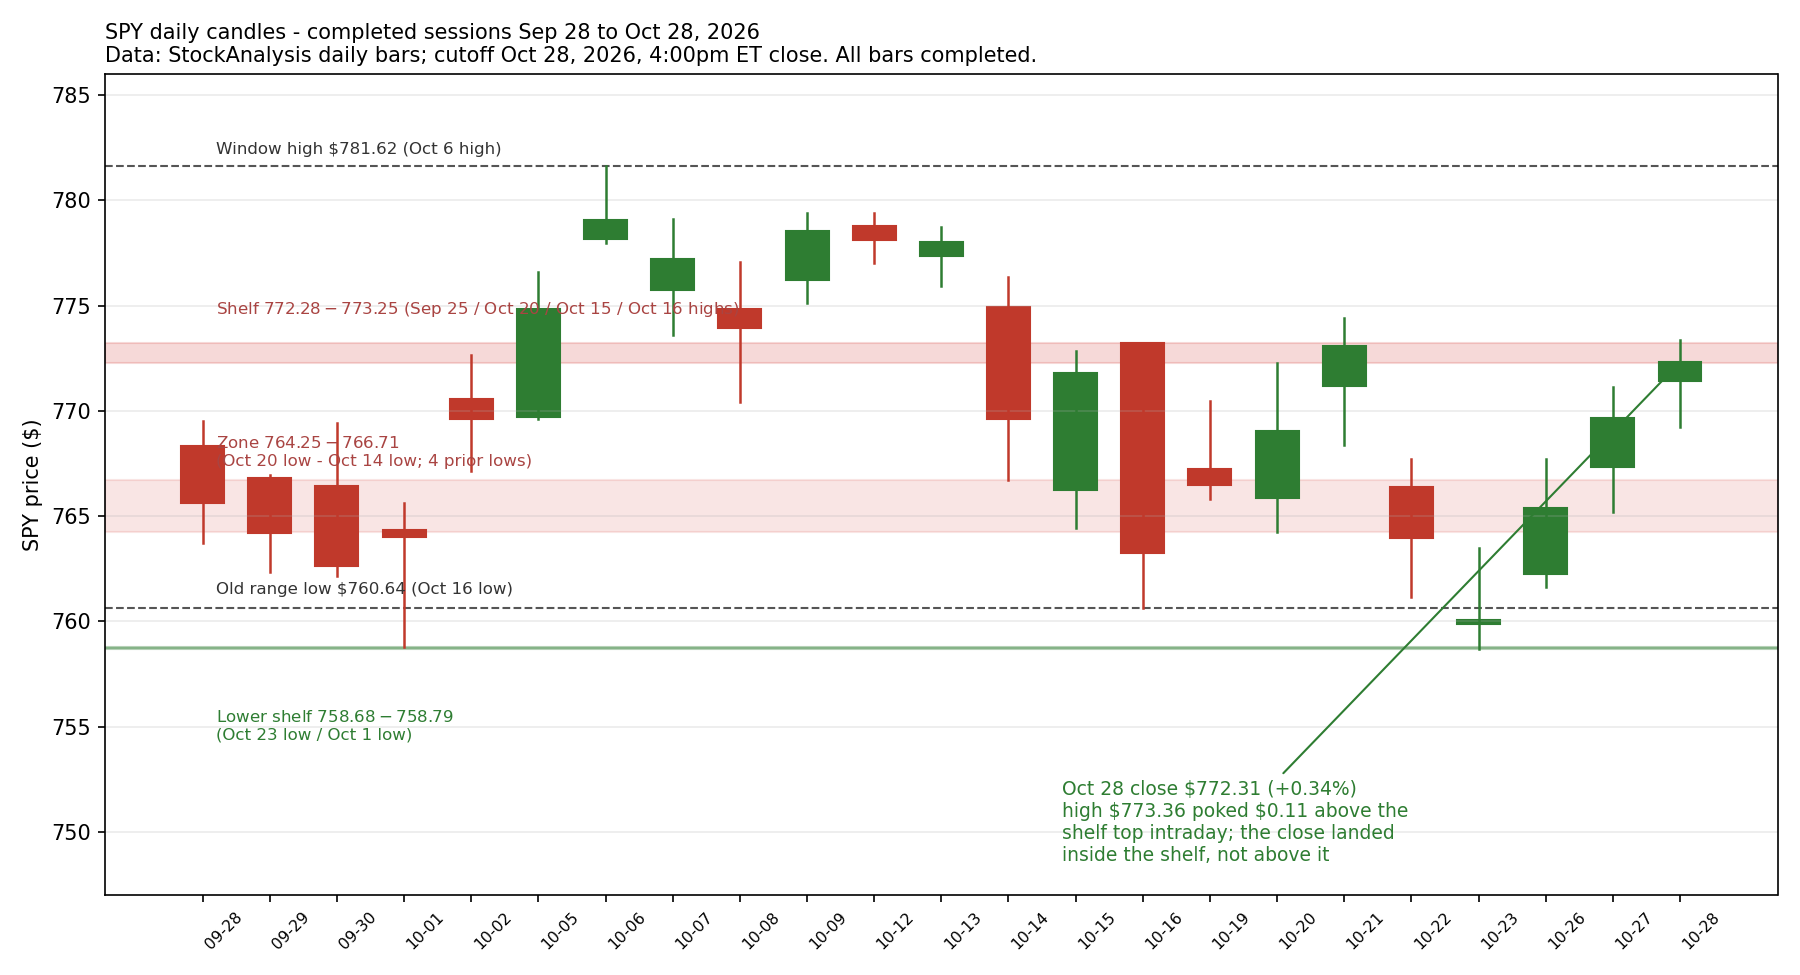
An intraday poke through a shelf top is not a close through it. SPY's $772.28-$773.25 shelf is built from four prior completed highs (StockAnalysis daily bars): Wednesday's completed bar reached $773.36, $0.11 above the shelf top (the Oct 16 high), and closed at $772.31 — inside the shelf, $0.03 above its bottom — so the shelf test is unpassed on a closing basis, the same grade the Oct 21 bar earned when it closed at $773.09 inside the shelf after a $774.44 high. The next rung of evidence would be a completed close above $773.25, and a stronger one a later dip toward the shelf that closes above it. What would weaken the lesson: a completed close back below $766.71, the zone top (the Oct 14 low), would put price back inside the cleared zone and weaken the repair.
Brief analysis source: SPY daily bars, StockAnalysis, Oct 28, 2026 (completed close) . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- On completed bars, SPY closed Wednesday at $772.31, up 0.34% (StockAnalysis): the high of $773.36 poked $0.11 above the $772.28-$773.25 shelf top, but the close landed inside the shelf — not a completed close above it — and the $769.24 low stayed above the $766.71 zone top, so the cleared zone was not retested.
- The Fed held at 3.75-4.00% in a 10-2 vote with two hike dissents, the 10-year yield closed near 5.04% and a December hike was priced at about 85% (CME FedWatch via Investopedia); Q3 GDP, September PCE and jobless claims all land tomorrow at 8:30am ET, with Amazon after the close.
- Options learning point: an intraday poke through a shelf is not a close through it — confirmation is graded — and any premium sold tonight must survive split after-hours reactions in big tech plus tomorrow's GDP and PCE, while waiting puts no option premium at risk.
Read the full brief and sources
- Start with the widest frame, on completed daily bars. SPY (the S&P 500 ETF) on Wednesday opened at $771.43, reached $773.36, held a low of $769.24 and closed at $772.31, up 0.34% (StockAnalysis daily bars). The Sep 28-Oct 28 completed window still runs from $781.62 (the Oct 6 high) down to $758.68 (the Oct 23 low), so today's close sits inside that wider range, about 1.2% below its high. This morning's brief set two tests: the $772.28-$773.25 shelf overhead and the Fed. The shelf test graded short of a pass — the high poked $0.11 above the shelf top intraday, but the completed close landed inside the shelf, $0.03 above its bottom, and a shelf break confirms only on a completed close beyond the zone plus a held retest. The low of $769.24 stayed above the $766.71 zone top, so the zone cleared on Tuesday was not retested today either.
- Inside that frame, the shelf has now absorbed two probes without a closing break. The $772.28-$773.25 shelf is built from four prior highs — the Sep 25 high ($772.28), the Oct 20 high ($772.29), the Oct 15 high ($772.87) and the Oct 16 high ($773.25) — and the Oct 21 completed bar also closed inside it, at $773.09 after a $774.44 high. Below the close, the first support area is the zone cleared on Tuesday, $764.25-$766.71 (four prior lows: Oct 20, Oct 15, Oct 19 and Oct 14), then the old reference-range low at $760.64 (the Oct 16 low), then the thin lower shelf at $758.68-$758.79 (the Oct 23 and Oct 1 lows, two touches). QQQ (the Nasdaq-100 ETF) closed at $725.61, up 0.60%, and IWM (the Russell 2000 ETF) at $281.29, up 0.40% (StockAnalysis, completed bars — ETF figures, not index levels), so growth and small caps both took part in the day's modest gain.
- The index closes matched the ETF read: the S&P 500 rose 0.3%, the Nasdaq Composite 0.3% and the Dow 0.2% (Investopedia closing recap). The day's scheduled event landed as priced: the Federal Reserve held rates at 3.75-4.00% in a 10-2 vote, with Lisa Cook and Beth Hammack dissenting in favor of a 25bp hike (Reuters), and a December hike was priced at about 85% afterwards (CME FedWatch via Investopedia). Single stocks moved more than the indexes: Oracle rose 11% on a stronger long-term revenue forecast, Vertiv rose 16%, Micron 6% and SK Hynix's US shares 13%, while Enphase fell 16% and Logitech 12% (Investopedia). No sourced breadth figure for today's close — the share of S&P 500 members above their 50-day average — had been published at this check; the latest available reading remains Monday's 60.8% (Market Scholars, Oct 26), so no breadth claim is made for today.
- Rates stayed the constraint after the decision. The 10-year Treasury yield closed near 5.04%, up more than 4bp from Tuesday's 4.99% close (Investopedia), and a Reuters market reaction put the yield at 5.047% shortly after the decision, with the 2-year at 4.776%. WTI crude settled at $102.55, up 2.6%, Brent near $115.10, up 1.1%, gold futures at $4,080, up 0.1%, bitcoin near $81,500 (Investopedia closing recap) and ether near $2,351 (CoinGecko via Investing Plus). The firmer yields coincided with the hold decision and the two hike dissents; which of those did the work is interpretation, not something the day's data proves.
- Tonight's after-close earnings are a separate, later development: today's 4:00pm ET close came before them and is not graded by them. Verified from official releases: Microsoft reported fiscal Q1 2027 GAAP diluted EPS of $4.92 and non-GAAP diluted EPS of $4.89 on revenue of $92,279M, up 19%, with Azure up 48% and Microsoft Cloud revenue up 30% (Microsoft investor relations), and its shares rose about 5% after hours (Barron's). Alphabet reported GAAP diluted EPS of $2.12 on revenue of $127,577M, up 25% — just below the $127.9B FactSet consensus — with Google Cloud up 103% and capital spending of $51.4B (Alphabet's release, furnished as an SEC Form 8-K exhibit), and its shares fell about 7% after hours (WSJ). T-Mobile reported diluted EPS of $3.22, up 34%, on revenue of $23,584M (Business Wire); ServiceNow, Fortinet, eBay and Ford also reported after the close, with their verified figures in the earnings panel. A question to study, not a trade: does Alphabet's $51.4B quarter of capital spending, read against Microsoft's cloud growth, change the AI-spending read-through into Amazon's report tomorrow night?
Analyst interpretation: the morning's two tests split. The Fed test is done — a hold, but with two dissents favoring a hike and the 10-year yield closing near 5.04%, the December pricing (about 85% for a hike) keeps event risk live into tomorrow's GDP and PCE. The shelf test is not done: a $0.11 intraday poke above $773.25 that closes at $772.31, inside the shelf, is a probe, not a break, and the same shelf absorbed the Oct 21 probe the same way. Through a conservative put-seller's lens, the structure argues for patience: price sits inside a four-touch shelf with a data-heavy morning ahead. A hypothetical teaching example only — not a market quote and not a trade: a $10-wide put credit spread (sell one put, buy a lower-strike put with the same expiry, in the Options Industry Council's definition) sold for a hypothetical $2.80 credit has a maximum gain of $2.80, a maximum loss of $7.20 plus fees, and a breakeven at the short strike minus $2.80. If the underlying finishes between the strikes at expiry with the spread worth $5.00, the loss is $2.20 before fees — the full $7.20 is lost only at or below the long strike — and the short put carries assignment risk before expiry. Waiting puts no option premium at risk; its cost is possibly missing a further move, not a spread loss.
A completed close above $773.25, the top of the $772.28-$773.25 shelf (the Oct 16 high), would be the first closing evidence through the shelf — a narrow pass on its own; a later session that dips toward the shelf or the $766.71 zone top (the Oct 14 low) and closes above it would grade the retest as held, which is stronger evidence.
A completed close back below $766.71, the zone top (the Oct 14 low), would put SPY inside the $764.25-$766.71 zone again and grade the closes above it as a false break; a completed close below $764.25, the zone bottom (the Oct 20 low), would reopen the $760.64 old range low (the Oct 16 low) as the next test.
Opened a position, added to an existing position and closed a position — traced to confirmed fills dated Oct 28 in the activity record; no names, strikes or dollar amounts are stated here, and exact execution detail stays pending sheet reconciliation.
Sources
- SPY daily bars (open/high/low/close) — StockAnalysisOct 28, 2026, 4:00pm ET close (completed bars through Oct 28)
- QQQ daily bars: Oct 28 close $725.61, up 0.60% — StockAnalysisOct 28, 2026, 4:00pm ET close (completed bars through Oct 28)
- IWM daily bars: Oct 28 close $281.29, up 0.40% (ETF figures, not the Russell 2000 index level) — StockAnalysisOct 28, 2026, 4:00pm ET close (completed bars through Oct 28)
- Closing recap: S&P 500 +0.3%, Nasdaq Composite +0.3%, Dow +0.2%; movers (Oracle +11%, Vertiv +16%, Micron +6%, Enphase -16%, Logitech -12%); 10-year yield near 5.04%; WTI $102.55, Brent ~$115.10, gold $4,080, bitcoin ~$81,500; December hike priced ~85% (CME FedWatch) — InvestopediaOct 28, 2026, after the 4:00pm ET close
- Fed holds at 3.75-4.00% in a 10-2 vote; Cook and Hammack dissented in favor of a 25bp hike; post-decision yields: 2-year 4.776%, 10-year 5.047% — ReutersOct 28, 2026, after the 2:00pm ET decision
- S&P 500 breadth: 60.8% of members above their 50-day average at Monday's close — the latest published reading at this check; no Oct 28 figure published — Market ScholarsOct 26, 2026 close
- Microsoft fiscal Q1 2027 results: GAAP diluted EPS $4.92, non-GAAP diluted EPS $4.89, revenue $92,279M, Azure +48% — Microsoft investor relationsOct 28, 2026, after the close
- Alphabet Q3 2026 results (release furnished as SEC Form 8-K Exhibit 99.1): GAAP diluted EPS $2.12, revenue $127,577M, Google Cloud +103%, capital expenditures $51.4B — Alphabet via Seeking Alpha press-release pageOct 28, 2026, after the close
- T-Mobile Q3 2026 results: diluted EPS $3.22, total revenues $23,584M — Business WireOct 28, 2026, after the close
- Ether (ETH) near $2,351 on Oct 28 — CoinGecko via Investing Plus; market data via FinnhubOct 28, 2026, post-close check