
Daily brief · 2026-10-27
Historical edition · New York time. These observations reflect their published date, not current market conditions.
SPY closes back above $760.64 — Friday's break graded false, zone top still ahead
false break on one close, reclaim unfinished: SPY back above the old range low but closing inside the zone, 10-year near 5% into the FOMC
Chart analysis
Published chart · Tap chart to enlarge.
Published chart lesson
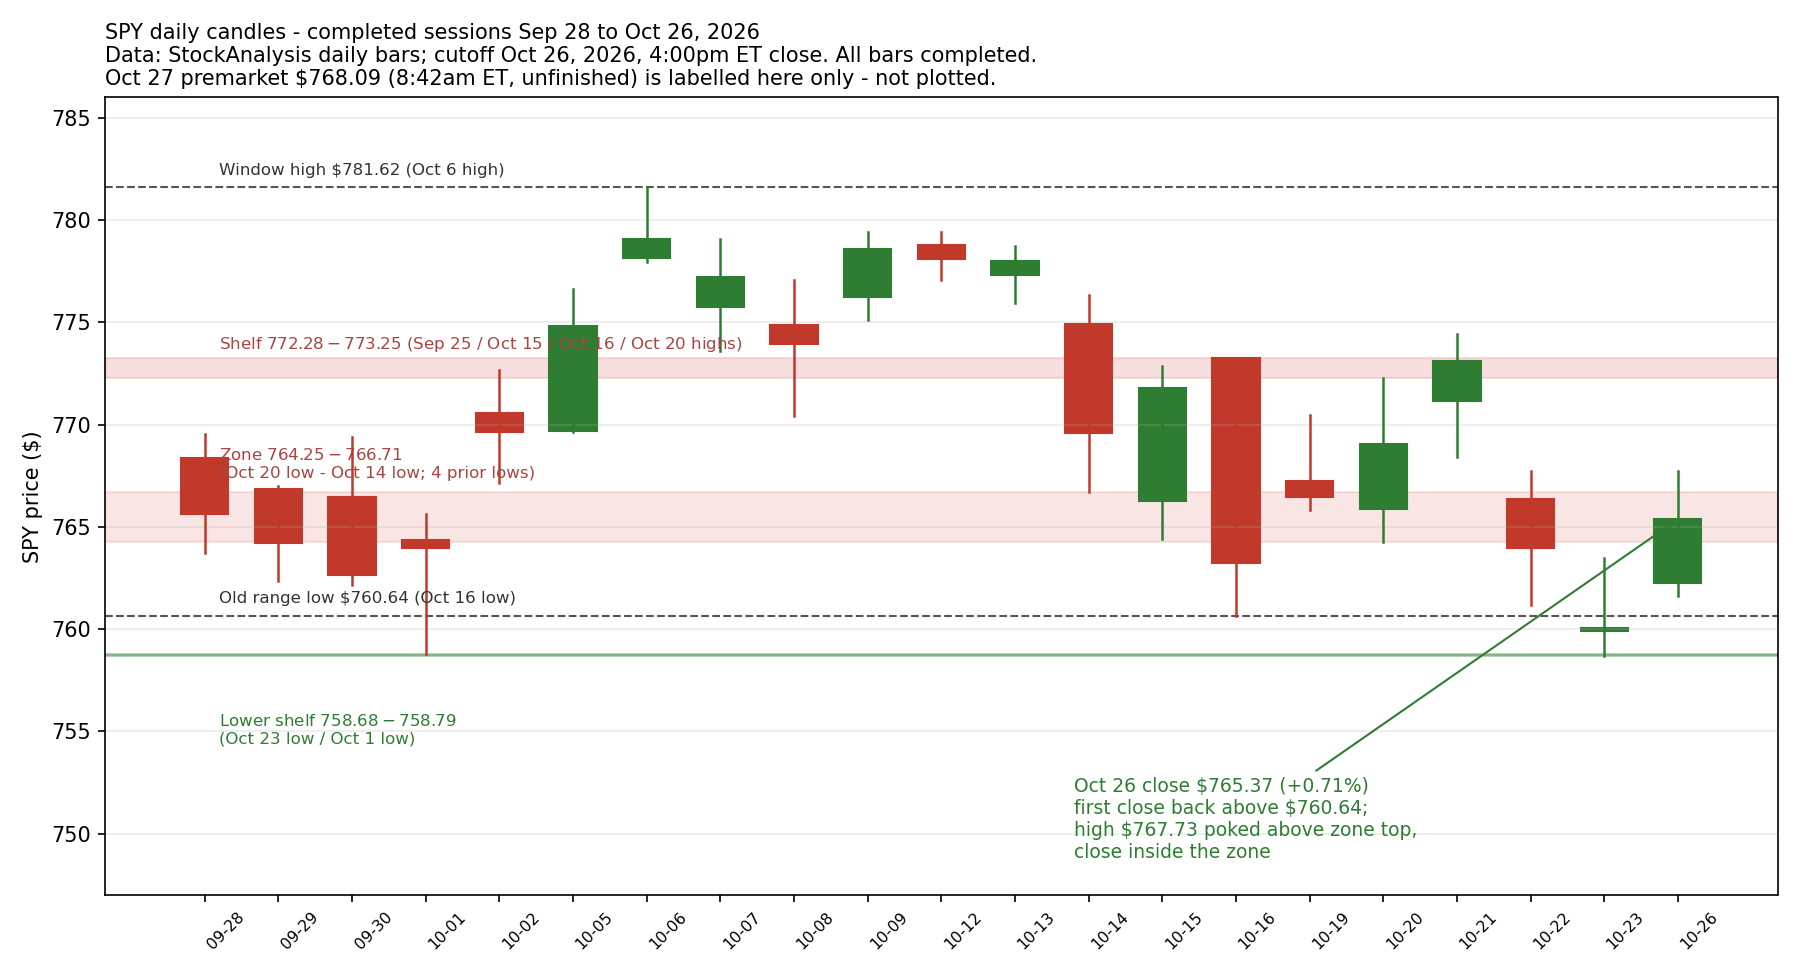
A false break is graded by the close back inside, and one close is only a narrow pass. SPY's $760.64 range low was set by the Oct 16 completed low (StockAnalysis daily bars): Friday's completed close of $759.97 landed below it, and Monday's completed bar — low $761.63, close $765.37 — never traded below the level and closed back above it, which grades Friday's push a false break. Stronger evidence would be a later retest of $760.64 from above that holds on a completed close; the reclaim close alone is the weakest rung of that ladder. The lesson weakens if a completed close lands back below $760.64, which would reinstate the break and show the level still decides the argument.
Brief analysis source: SPY daily bars, StockAnalysis historical data, completed sessions through Oct 26, 2026 close (Oct 26 bar: open $762.25, high $767.73, low $761.63, close $765.37); premarket indication StockAnalysis, Oct 27, 2026, 8:42am ET (unfinished). Annotated chart: /today/2026-10-27-spy-false-break-zone.png (same SPY daily series, completed through Oct 26 close; premarket labelled, not plotted). . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- On completed bars, SPY closed Monday at $765.37 — the first completed close back above the $760.64 Oct 12-22 reference-range low (Oct 16 low, StockAnalysis) — so Friday's one-close break is graded a false break, but the close sits inside the $764.25-$766.71 zone rather than above it.
- September durable goods orders rose 1.8% at 8:30am ET, close to the +1.7% consensus (U.S. Census Bureau); the week's larger tests are tomorrow's 2:00pm ET FOMC decision (a hold priced at about 90%) and Thursday's Q3 GDP and Core PCE at 8:30am ET.
- Options learning point: one close back inside grades a false break, and grading is a ladder, not a switch — a held retest of the reclaimed level is stronger evidence than the reclaim close itself, and any premium sold today still has to survive tomorrow's FOMC and Thursday's inflation data.
Read the full brief and sources
- Start with the widest frame, on completed daily bars. SPY (the S&P 500 ETF) on Monday opened at $762.25, reached $767.73, held a low of $761.63 and closed at $765.37, up 0.71% (StockAnalysis daily bars) — the first completed close back above $760.64, the Oct 16 low that set the bottom of the Oct 12-22 reference range (top $779.40, the Oct 12 high). By the grading this brief uses, Friday's single close below that low is now graded a false break: Monday's low stayed $0.99 above $760.64 and the close landed back inside the range. That is one close, a narrow pass, not a trend claim: the wider Sep 28-Oct 26 completed window still runs from $781.62 (Oct 6 high) down to $758.68 (Oct 23 low), and the last completed week (Oct 19-23) closed at $759.97 near its low before Monday's reclaim.
- Inside that frame, the reclaim is unfinished because the close stopped inside the next zone, not above it. The $764.25-$766.71 zone is built from four prior lows — the Oct 20 low ($764.25), the Oct 15 low ($764.43), the Oct 19 low ($765.82) and the Oct 14 low ($766.71) at its top — and Monday's high of $767.73 poked $1.02 above the zone top before the $765.37 close fell back inside it; an intraday poke is not a close. Above the zone sits the $772.28-$773.25 shelf, built from the Sep 25 high ($772.28), the Oct 20 high ($772.29), the Oct 15 high ($772.87) and the Oct 16 high ($773.25). Below, the first supports are the old range low at $760.64 and then the thin lower shelf at $758.68-$758.79 (the Oct 23 and Oct 1 lows, two touches). QQQ (the Nasdaq-100 ETF) closed stronger: open $707.06, high $715.25, low $705.58, close $712.20, up 1.11% (StockAnalysis, completed bar).
- This morning's 8:30am ET release was September durable goods orders: new orders rose 1.8% to $345.4 billion, up six of the last seven months, against a +1.7% consensus (U.S. Census Bureau advance report CB 26-169; consensus from the WSJ survey via Morningstar); orders excluding transportation rose 0.5%, and transportation equipment led, up 4.6% to $119.8 billion. A roughly in-line firm print changes little ahead of tomorrow's FOMC decision, and this morning's unfinished prints lean up without grading anything: SPY traded at $768.09 in premarket at 8:42am ET, up 0.36% (StockAnalysis, unfinished) — above the $766.71 zone top, but only a completed close can grade that test — and QQQ traded at $715.72 at 8:43am ET, up 0.49% (unfinished). S&P 500 futures were up 0.28% and Dow futures up 0.21% in Barron's premarket check, and the 10-year Treasury yield was 4.971% (Barron's) to 4.98% (Investopedia), little changed near 5%. October consumer confidence and September new home sales follow at 10:00am ET.
- Breadth supports the steadier read, rates still argue for patience. At Monday's close, 60.8% of S&P 500 members were above their 50-day average — 304 stocks, up from 294 (Market Scholars market internals, Oct 26) — so the reclaim coincided with wider participation, not just the index. The other side of the ledger is the calendar and the level of yields: the FOMC meets today and decides tomorrow at 2:00pm ET with a hold at 3.75-4.00% priced at about 90% (CME FedWatch via VaultEdge, Oct 26), while the 10-year yield holds just under 5%. Overnight, Japan's Nikkei 225 rose 1.73% while China's Shanghai Composite fell 1.33% (Barron's); WTI crude futures were down 0.7% at $101.05, gold futures down 0.4% to $4,025, and bitcoin had slipped below $80,000 (Investopedia; Barron's put bitcoin at $79,766, down 0.15%).
- This morning's BMO earnings, verified from official releases, were led by Coca-Cola: EPS of $0.93 and comparable EPS of $0.91 on net revenues of $13.4 billion, up 7%, with full-year guidance raised (Business Wire). UPS reported diluted EPS of $1.37 and adjusted diluted EPS of $1.69; Royal Caribbean reported GAAP EPS of $6.45 and adjusted EPS of $6.57; HCA Healthcare reported GAAP diluted EPS of $7.27 and adjusted EPS of $7.22; SoFi reported GAAP EPS of $0.18 on record net revenue and raised its full-year guide. Monday's after-close standout also belongs in this morning's picture: Celestica, carried as pending from yesterday's reconciliation check, reported GAAP EPS of $3.26 and adjusted EPS of $3.30 on revenue of $5.83 billion — above the high end of its own guidance — and was up 15.7% in premarket (Barron's). Not every name is settled: S&P Global and Freeport-McMoRan posted releases that point to investor-relations supplements for their figures, so their EPS stays unverified on the reconciliation queue rather than guessed. A question to study, not a trade: do this morning's consumer- and travel-facing beats stay a large-cap story, or widen into Alphabet and Microsoft tomorrow?
Analyst interpretation: Monday's close cancels Friday's break on the only basis that grades it — a completed close — but it is a narrow pass, and the price stopped inside the $764.25-$766.71 zone it still has to clear. The steadier side has real evidence: the reclaim close, QQQ up 1.11%, and 60.8% of members above their 50-day average. The cautious side is just as concrete: a 10-year yield just under 5%, an FOMC decision tomorrow, and GDP with Core PCE on Thursday. Through a conservative put-seller's lens, that event stack matters more than one green close. A hypothetical teaching example only — not a market quote and not a trade: a $10-wide put credit spread (sell one put, buy a lower-strike put with the same expiry, in the Options Industry Council's definition) sold for a hypothetical $2.80 credit has a maximum gain of $2.80, a maximum loss of $7.20 plus fees, and a breakeven at the short strike minus $2.80. If the underlying finishes between the strikes at expiry with the spread worth $5.00, the loss is $2.20 before fees — the full $7.20 is lost only at or below the long strike — and the short put carries assignment risk before expiry. Waiting puts no option premium at risk; its cost is possibly missing a further reclaim, not a spread loss. Mid-box, with the zone top untested on a closing basis, waiting is a valid position.
The reclaim strengthens if SPY posts a completed close above $766.71 — the Oct 14 low that forms the top of the $764.25-$766.71 zone — and then holds above that zone on a retest from above on a completed-close basis; a completed close above the $772.28-$773.25 shelf (the Sep 25, Oct 15, Oct 16 and Oct 20 highs) would be stronger evidence still. Premarket or intraday prints above the zone, like this morning's $768.09 unfinished indication, do not grade the test.
The reclaim fails if SPY posts a completed close back below $760.64 — the Oct 16 low that set the bottom of the Oct 12-22 reference range — which would reinstate Friday's range break; a completed close below the $758.68-$758.79 lower shelf (the Oct 23 and Oct 1 lows) would be stronger evidence against the reclaim than a close between $760.64 and that shelf.
Sources
- SPY daily bars: Oct 26 open $762.25, high $767.73, low $761.63, close $765.37 (+0.71%); Oct 23 close $759.97; Sep 28-Oct 26 window high $781.62 (Oct 6), window low $758.68 (Oct 23); Oct 12-22 reference range $760.64 (Oct 16 low) to $779.40 (Oct 12 high); zone lows $764.25 (Oct 20), $764.43 (Oct 15), $765.82 (Oct 19), $766.71 (Oct 14); shelf highs $772.28 (Sep 25), $772.29 (Oct 20), $772.87 (Oct 15), $773.25 (Oct 16); Oct 1 low $758.79 — StockAnalysis historical dataCompleted sessions through Oct 26, 2026, 4:00pm ET close
- SPY premarket $768.09, +0.36% (unfinished indication) — StockAnalysisOct 27, 2026, 8:42am ET (premarket, unfinished)
- QQQ daily bar Oct 26: open $707.06, high $715.25, low $705.58, close $712.20 (+1.11%); QQQ premarket $715.72, +0.49% (unfinished) — StockAnalysis historical dataCompleted sessions through Oct 26, 2026; premarket Oct 27, 2026, 8:43am ET (unfinished)
- September durable goods orders: new orders +1.8% to $345.4 billion (up six of the last seven months, after a +0.1% August increase), ex-transportation +0.5%, ex-defense +2.2%, transportation equipment +4.6% to $119.8 billion — U.S. Census Bureau advance report CB 26-169Released Oct 27, 2026, 8:30am ET
- WSJ survey consensus via Dow Jones: durable goods +1.7%, consumer confidence 81.0 (previous 81.9), new home sales 653K, Q3 GDP +3.1%, Core PCE +0.3% m/m — Morningstar (Dow Jones Newswires data week ahead)Oct 26, 2026, 13:57 ET
- Premarket: S&P 500 futures up 0.28%, Dow futures up 0.21%, VIX futures down 1.54%, 10-year Treasury yield 4.971%, Brent crude futures down 0.89%, gold futures down 0.35%, bitcoin $79,766 (-0.15%), Nikkei 225 up 1.73%, Shanghai Composite down 1.33%, Celestica up 15.7% premarket — Barron's (Dow Jones/FactSet data)Oct 27, 2026, premarket (about two hours before the 9:30am ET open)
- Futures higher recently (Dow and S&P 500 +0.2%, Nasdaq +0.4%); WTI crude futures down 0.7% at $101.05, gold futures down 0.4% to $4,025, bitcoin slipped below $80,000, 10-year Treasury yield ticked lower to 4.98% from 4.99%; UPS, Royal Caribbean and Coca-Cola posted better-than-expected earnings; the Fed begins its two-day meeting today — InvestopediaOct 27, 2026, before the open
- S&P 500 breadth at the Oct 26 close: 60.8% of members above their 50-day average (304 stocks, up from 294, about 58.8%); bullish percent 51.0 — Market Scholars market internalsOct 26, 2026, market close
- CME FedWatch: odds of a hold at 3.75-4.00% at the Oct 27-28 FOMC about 90%; a December hike priced at roughly 75-80% — VaultEdge citing CME FedWatchOct 26, 2026
- Coca-Cola Q3 2026 official release: EPS $0.93, comparable EPS $0.91, net revenues $13.4 billion (+7%), full-year guidance raised — Business WireOct 27, 2026, before the open
- UPS Q3 2026 official release: diluted EPS $1.37, adjusted diluted EPS $1.69 — Business WireOct 27, 2026, before the open
- Royal Caribbean Q3 2026 official release: GAAP EPS $6.45, adjusted EPS $6.57 — PR Newswire (PRN Asia republication)Oct 27, 2026, before the open
- HCA Healthcare Q3 2026 official release: GAAP diluted EPS $7.27, adjusted EPS $7.22 — Business WireOct 27, 2026, before the open
- Celestica Q3 2026 official release (GlobeNewswire, Morningstar republication): revenue $5.83 billion (+83%), GAAP EPS $3.26, adjusted EPS $3.30, above the high end of guidance; full-year revenue outlook raised to $21.0 billion — CelesticaOct 26, 2026, after the close
SPY closes above the zone at $769.66 — the $772.28-$773.25 shelf is next
zone cleared on a completed close, shelf untested: chips led, the Dow flat on Boeing, 10-year near 4.99% into the FOMC
Chart analysis
Published chart · Tap chart to enlarge.
Published chart lesson
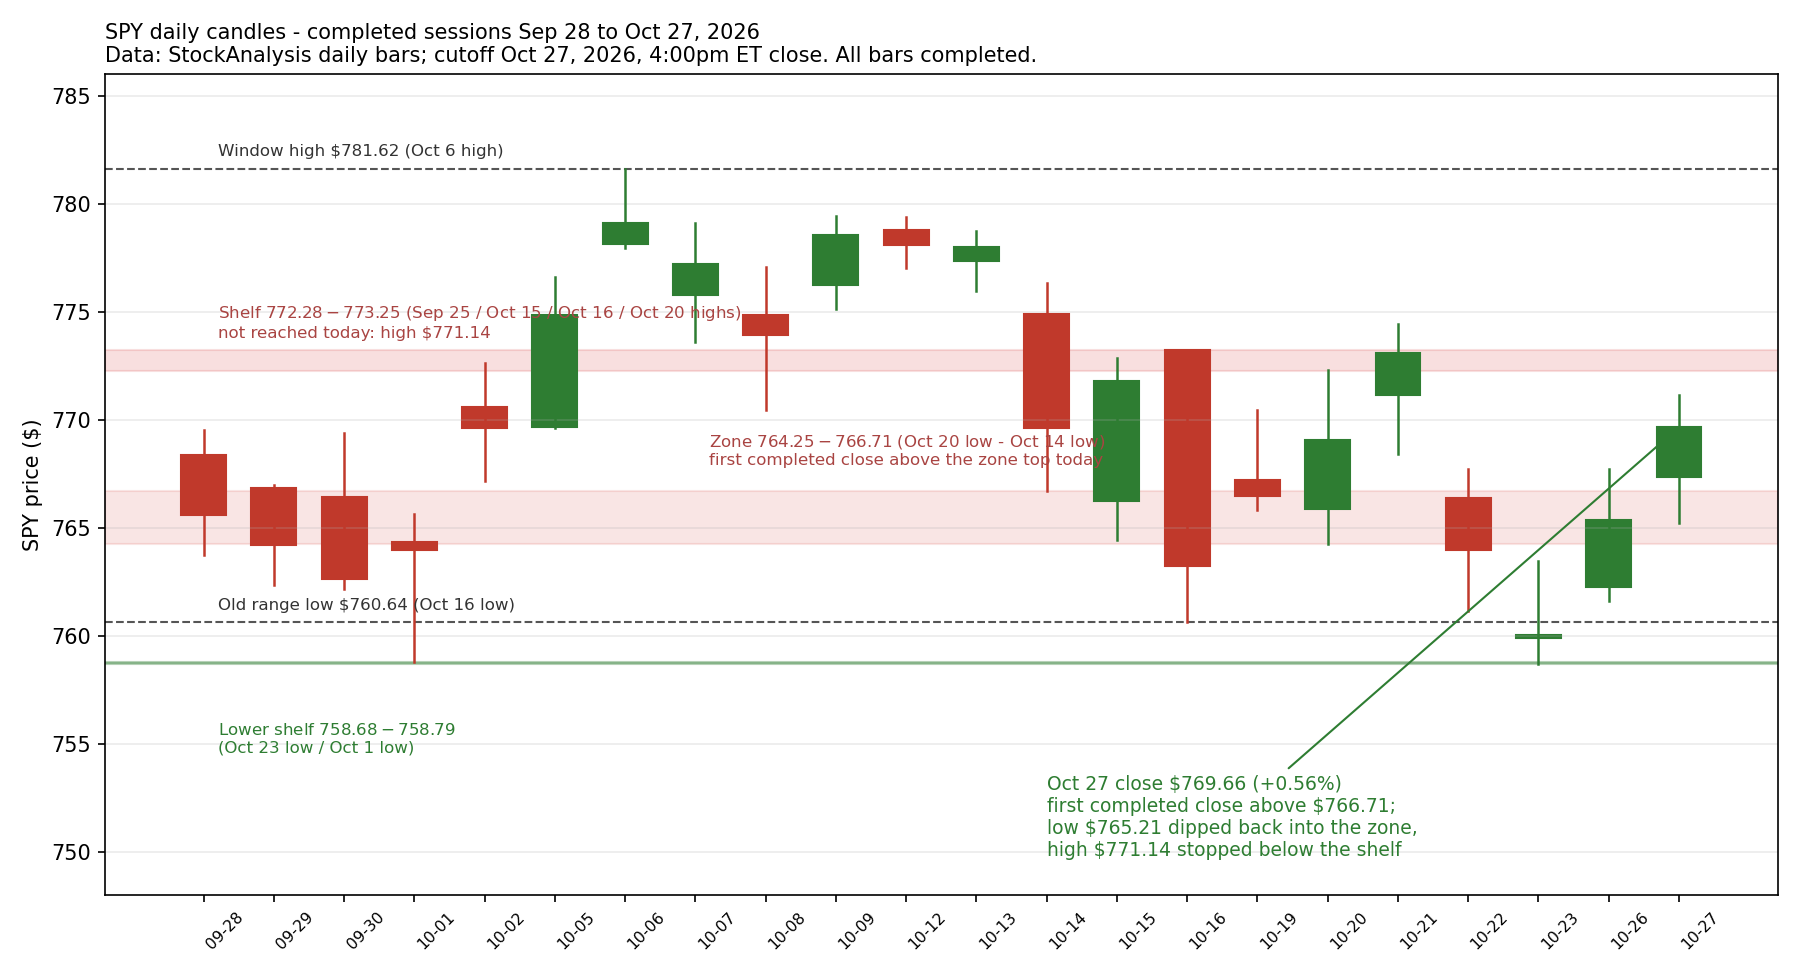
A close above a zone is the first rung of confirmation, and an intraday dip back into the zone is not a retest. SPY's $764.25-$766.71 zone is built from prior lows (its top is the Oct 14 low at $766.71; its bottom is the Oct 20 low at $764.25): Monday's completed close of $765.37 landed inside it, and Tuesday's completed bar dipped to a low of $765.21 — back inside the zone intraday — before closing at $769.66, above the zone top (StockAnalysis daily bars, completed Oct 27 bar). That grades the zone test as passed on a closing basis, one rung only: the stronger evidence would be a later completed close that retests $766.71 from above and holds. The lesson weakens if a completed close lands back below $766.71, which would put price inside the zone again and show the top has not yet become a floor.
Brief analysis source: SPY daily bars, StockAnalysis historical data, completed sessions through Oct 27, 2026 close (Oct 27 bar: open $767.34, high $771.14, low $765.21, close $769.66). Annotated chart: /today/2026-10-27-spy-zone-clear-shelf.png (same SPY daily series, completed through Oct 27 close). . Chart uses its own dated Yahoo series; vendor levels can differ.
Three key points
- On completed daily bars, SPY closed at $769.66 — the first completed close above the $764.25-$766.71 zone top at $766.71 (the Oct 14 low, StockAnalysis) — while the day's $771.14 high stopped below the $772.28-$773.25 shelf built from four prior highs.
- The S&P 500 index rose 0.6% to 7,722.62 and the Nasdaq Composite rose 1.18% to 26,477.81 (Gate market data via ChainCatcher), with chips leading and Boeing's fall of nearly 11% holding the Dow to a 0.03% gain; the 10-year Treasury yield ended near 4.99% into tomorrow's 2:00pm ET FOMC decision.
- Options learning point: a completed close above a zone is the first rung of confirmation, not the last — a retest of the zone top that holds on a completed close is stronger evidence, and any premium sold tonight still has to survive tomorrow's FOMC decision and Thursday's GDP and Core PCE data.
Read the full brief and sources
- Start with the widest frame, on completed daily bars. SPY (the S&P 500 ETF) on Tuesday opened at $767.34, reached $771.14, held a low of $765.21 and closed at $769.66, up 0.56% (StockAnalysis daily bars) — the first completed close above $766.71, the Oct 14 low that forms the top of the $764.25-$766.71 zone, which is the grade the morning brief set for the zone test: a completed close above the zone, not Monday's intraday poke above it. The wider frame is unchanged by one close: the Sep 28-Oct 27 completed window still runs from $781.62 (the Oct 6 high) down to $758.68 (the Oct 23 low), with the Oct 12-22 reference range inside it ($760.64, the Oct 16 low, to $779.40, the Oct 12 high) — today repaired the zone, not the whole window.
- Inside that frame, the next test is already named and was not reached. Above the close sits the $772.28-$773.25 shelf, built from four prior highs — Sep 25 ($772.28), Oct 20 ($772.29), Oct 15 ($772.87) and Oct 16 ($773.25) — and Tuesday's high of $771.14 stopped $1.14 below its bottom (completed daily bar). The day also gave the zone a first look from above: the low of $765.21 dipped $1.50 below the zone top but stayed above the zone bottom at $764.25 (the Oct 20 low), and the close landed back above the top. An intraday dip is not a completed-close retest, so the retest grade stays open; below the zone, the old range low at $760.64 and then the lower shelf at $758.68-$758.79 (the Oct 23 and Oct 1 lows, two touches) are unchanged.
- The index closes agree with the ETF read, and the split underneath was uneven. The S&P 500 index rose 45.85 points (0.6%) to 7,722.62, the Nasdaq Composite rose 308.43 points (1.18%) to 26,477.81 and the Dow Jones Industrial Average rose 15.99 points (0.03%) to 52,377.57 (Gate market data via ChainCatcher); no record closes were reported in the sources checked. QQQ (the Nasdaq-100 ETF) closed at $721.25, up 1.27%, and IWM (the Russell 2000 ETF) rose 1.15% to $280.18 (StockAnalysis, completed bars — ETF figures, not index levels), so growth and small caps both took part. Chips carried the headline: the iShares Semiconductor ETF (SOXX) ended almost 4% higher and the Roundhill Memory ETF (DRAM) roughly 4.5% higher (Investopedia), and Broadcom closed up 4.00% at $342.33 (Motley Fool), while Boeing's fall of nearly 11% held the Dow to a fractional gain. A sourced breadth figure for today's close — the share of S&P 500 members above their 50-day average — was not yet published at this check; the latest sourced reading remains Monday's 60.8% (Market Scholars, Oct 26), so no breadth claim is made for today.
- Rates stayed the brake while the day's data came in firmer than expected. The 10-year Treasury yield rose 0.004 percentage point to 4.992% (Dow Jones Data Talk, based on 3:00pm ET values). October consumer confidence rose to 91.7, above the 81.0 consensus and September's revised 84.2 (Conference Board), September new home sales ran at a 676,000 annual pace against a 653,000 consensus (U.S. Census Bureau), and the morning's September durable goods orders had risen 1.8% — firm data that coincided with a 10-year yield holding just under 5% on the day before the FOMC decision, not a proven cause of the stock move. WTI crude futures fell 1.9% to below $100 a barrel and front-month Brent fell 1.7% to below $114, gold futures rose 0.9% to $4,075 an ounce, bitcoin traded around $80,600 and ether near $2,346 (Investopedia; Finnhub).
- Tonight's after-close earnings are a separate, later development — today's 4:00pm ET close precedes them, and the next full session grades them. Verified from official releases: Visa reported fiscal fourth-quarter GAAP EPS of $3.19 and non-GAAP EPS of $3.48 on net revenue of $12.14 billion, up 13%, against a $3.44 adjusted consensus and $12.09 billion revenue consensus (FactSet via WSJ), and fell 1.1% in after-hours trading (WSJ). Seagate reported fiscal first-quarter 2027 GAAP diluted EPS of $7.59 and non-GAAP diluted EPS of $7.68 on revenue of $4.23 billion (Business Wire release). Robinhood's official release text had not been opened at this check; Reuters reported net income of $476 million, or $0.51 a share, below the roughly $0.56 consensus, with shares down about 5% in after-hours trading (Reuters; WSJ), so its EPS stays on the reconciliation queue as released but not yet verified rather than recorded. Waste Management, NXP, ONEOK, Baker Hughes, Teradyne and Enphase had not released at this check and stay on the queue for the next run. A question to study, not a trade: what evidence in tomorrow's Alphabet and Microsoft releases would show whether AI spending is widening beyond the hardware names, or narrowing into them?
Analyst interpretation: today grades as a second, stronger rung for the repair — a completed close above the zone, after Monday's close back inside the old range — but the evidence stops there. The shelf at $772.28-$773.25 was not tested on a closing basis, the day's low dipped back into the zone it had just cleared, a sourced breadth figure for today's close was not yet available at this check, and the 10-year yield ended at 4.992%, still just under 5%. Through a conservative put-seller's lens, the calendar matters more than the colour of the close: tomorrow brings the FOMC decision at 2:00pm ET and Alphabet and Microsoft after the close, and Thursday brings GDP and Core PCE. A hypothetical teaching example only — not a market quote and not a trade: a $10-wide put credit spread (sell one put, buy a lower-strike put with the same expiry, in the Options Industry Council's definition) sold for a hypothetical $3.00 credit has a maximum gain of $3.00, a maximum loss of $7.00 plus fees, and a breakeven at the short strike minus $3.00. If the underlying finishes between the strikes at expiry with the spread worth $6.00, the loss is $3.00 before fees — the full $7.00 is lost only at or below the long strike — and the short put carries assignment risk before expiry. Waiting puts no option premium at risk; its cost is possibly missing a push into the shelf, not a spread loss. With the close above the zone but the shelf and the week's two biggest event days still ahead, patience remains the position the evidence supports.
The zone clear strengthens if SPY holds above the zone on a retest — a completed close that comes back to $766.71, the Oct 14 low that forms the top of the $764.25-$766.71 zone, and closes above it — or posts a completed close above the $772.28-$773.25 shelf (the Sep 25, Oct 15, Oct 16 and Oct 20 highs), which would be the next level of evidence. Intraday trades above the shelf, like today's $771.14 high below it, do not grade either test.
The clear weakens if SPY posts a completed close back below $766.71, which returns price to inside the $764.25-$766.71 zone; a completed close below the zone bottom at $764.25 (the Oct 20 low) would cancel the clear, and a completed close below $760.64 — the Oct 16 low that set the bottom of the Oct 12-22 reference range — would reinstate the range break the last two closes repaired.
Awaiting confirmation — no confirmed fills dated Oct 27 were in the activity record at this check (the latest logged fill is dated Oct 26); nothing is inferred about today's trading from missing records.
Sources
- SPY daily bars: Oct 27 open $767.34, high $771.14, low $765.21, close $769.66 (+0.56%); Oct 26 close $765.37; Sep 28-Oct 27 window high $781.62 (Oct 6), window low $758.68 (Oct 23); Oct 12-22 reference range $760.64 (Oct 16 low) to $779.40 (Oct 12 high); zone lows $764.25 (Oct 20), $764.43 (Oct 15), $765.82 (Oct 19), $766.71 (Oct 14); shelf highs $772.28 (Sep 25), $772.29 (Oct 20), $772.87 (Oct 15), $773.25 (Oct 16); Oct 1 low $758.79 — StockAnalysis historical dataCompleted sessions through Oct 27, 2026, 4:00pm ET close
- QQQ daily bar Oct 27: open $715.12, high $722.87, low $713.59, close $721.25 (+1.27%) — StockAnalysis historical dataCompleted sessions through Oct 27, 2026, 4:00pm ET close
- IWM (Russell 2000 ETF) daily bar Oct 27: open $277.96, high $280.40, low $276.89, close $280.18 (+1.15%) — StockAnalysis historical data (ETF figure, not the Russell 2000 index level, which was not separately verified in this check)Completed sessions through Oct 27, 2026, 4:00pm ET close
- Index closes Oct 27: S&P 500 index +45.85 points (+0.6%) to 7,722.62; Nasdaq Composite +308.43 points (+1.18%) to 26,477.81; Dow Jones Industrial Average +15.99 points (+0.03%) to 52,377.57 — Gate market data via ChainCatcherOct 27, 2026, 4:00pm ET close (reported after the close)
- Tech shares extended their rally and indexes ended higher ahead of the Fed decision; SOXX ended almost 4% higher, the Roundhill Memory ETF (DRAM) roughly 4.5% higher; Boeing fell nearly 11%, limiting the Dow; WTI crude futures pulled back 1.9% to below $100 a barrel around 4:00pm ET, Brent fell 1.7% to below $114; the 10-year Treasury yield was near 4.99%; bitcoin traded around $80,600; gold futures rose 0.9% to $4,075 an ounce; markets priced just a 7% likelihood of a Fed hike this week (CME FedWatch) — Investopedia markets recapOct 27, 2026, after the 4:00pm ET close
- 10-year Treasury yield rose 0.004 percentage point to 4.992%, based on 3:00pm ET values (Tradeweb FTSE closing prices); two-year yield 4.735% — Dow Jones Data Talk via Morningstar; WSJOct 27, 2026, 3:41pm ET (3:00pm ET values)
- October consumer confidence rose 7.5 points to 91.7, up from September's revised 84.2 (consensus about 81) — The Conference Board via PR NewswireReleased Oct 27, 2026, 10:00am ET
- September new home sales fell 0.6% to a seasonally adjusted annual rate of 676,000 (consensus about 653,000), with 8.4 months of supply — U.S. Census Bureau and HUD, via the National Association of Home BuildersReleased Oct 27, 2026
- S&P 500 breadth at the Oct 26 close: 60.8% of members above their 50-day average (304 stocks) — Market Scholars market internals (latest sourced reading at this check; no Oct 27 figure was published yet)Oct 26, 2026, market close
- Boeing shares plunged nearly 11% to close at $168.18 after management said 737 MAX deliveries would miss the roughly 500-jet target for 2026 and pushed out longer-term free cash flow goals; Q3 loss was $0.34 a share on sales of $24.1 billion — Barron'sOct 27, 2026, after the close
- Broadcom closed at $342.33, up 4.00%, after a DA Davidson upgrade and reports of a $63 billion financing arrangement for Anthropic's purchases of Broadcom AI accelerators and networking equipment — The Motley FoolOct 27, 2026, 4:00pm ET close
- Ether (ETH) traded near $2,346, up about 1.37% on the day — Finnhub market data (Binance)Oct 27, 2026, post-market check
- Visa fiscal Q4 2026 official release (SEC 8-K Exhibit 99.1, posted on Visa IR): GAAP EPS $3.19, non-GAAP EPS $3.48, net revenue $12.14 billion (+13%), dividend raised 16% to $0.78 — VisaOct 27, 2026, after the close
- Visa beat: adjusted EPS $3.48 against a $3.44 FactSet consensus and revenue of $12.14 billion against $12.09 billion expected; shares fell 1.1% to $397.26 in after-hours trading — WSJOct 27, 2026, after hours
- Robinhood Q3 2026: net income $476 million, or $0.51 a share, down from $556 million, or $0.61, a year earlier, as slower crypto trading weighed — Reuters (official release text not opened in this run; EPS not recorded as verified)Oct 27, 2026, after the close
- Week calendar: FOMC decision Wed Oct 28 at 2:00pm ET; Alphabet and Microsoft after Wed's close; Thu Oct 29 Caterpillar, Mastercard, Merck and Eli Lilly before the open and Amazon, Intel and Starbucks after the close; Fri Oct 30 Exxon, Chevron and AbbVie — PhilStockWorld calendar previewOct 27, 2026
- Data week ahead: Q3 GDP and September PCE/Core PCE on Thu Oct 29 and the Q3 employment cost index on Fri Oct 30 — Morningstar (Dow Jones Newswires data week ahead)Oct 26, 2026, 13:57 ET